RESEARCH / Investment data operations
Canoe Intelligence alternatives: fund-document automation and M&A tools
Compare Canoe with Alkymi, Accelex, Arch and portfolio platforms on portal collection, extraction, validation, integrations and the distinct needs of M&A teams.
Research as of
Website edition edited
Published by CorpDev.Ai, which is one of the vendors assessed. This analysis distinguishes vendor claims, external evidence and analyst judgments. Prices and capabilities reflect the source dates in the article; the website edition is an editorial adaptation, not a new verification of every claim.
Locate the document bottleneck before buying extraction capacity
Canoe addresses a specific operating burden: repeatedly collecting investment documents, extracting their contents and delivering validated data into downstream systems. That is an attractive automation problem when the team receives a continuing stream of fund statements, notices and reports. It is a different problem from analysing a target company’s data room or producing an acquisition recommendation, even though both involve reading financial documents with AI.
For an M&A VP overseeing corporate venture or a portfolio of fund commitments, both requirements may exist. The investment-operations purchase should then be justified by fewer collection failures, manageable exception queues and dependable reconciliation—not by a generic claim of document intelligence. A blind test of representative documents should include amendments, awkward layouts and conflicting values, with reviewers measuring the work required to resolve exceptions. Keep that decision separate from the analytical layer used for market research and diligence. Announced ownership changes in this category add a further practical issue: confirm the contracted product, integrations and support commitments instead of treating an acquiring company’s broader capabilities as already delivered.
Executive Summary
Canoe Intelligence is the clear leader in a narrow, valuable category — collecting and extracting alternative-investment documents for LPs, wealth managers and allocators — and it is about to become part of Bloomberg. For a corporate development, strategy or M&A professional, however, the decisive finding of this report is that Canoe and the tools most often compared with it do not compete for the same budget. Canoe processes documents you already receive; deal platforms such as CorpDev.Ai, Midaxo and Intapp DealCloud produce analysis and run processes you do not yet have. The question is not "Canoe or CorpDev.Ai" but "which of the two jobs is our bottleneck" — and for most corporate development teams without an LP portfolio, it is the second.
500+
Canoe institutional clients, $11T+ AUM/AUA
Jul 2026
Bloomberg agrees to acquire Canoe (pending)
5
Vendors in this set had completed or announced ownership changes in 14 months
2 of 12
Vendors with published pricing (Affinity, CorpDev.Ai)
Key findings
Three jobs, not one market. The landscape splits into alternatives data operations (Canoe, Alkymi, Accelex, Arch), deal-lifecycle workflow (DealCloud, Midaxo, Datasite, Affinity, CorpDev.Ai) and portfolio monitoring and analytics (Chronograph, MSCI Burgiss, Addepar, Allvue, eFront). Canoe scores best in class on the first and zero on the second by design; the third is its integration ecosystem rather than its competition [6][9][26].
Canoe's moat is collection breadth and ecosystem gravity. A 3,000-portal retrieval network, bounded field-level extraction with up to 100 validation checks, and production integrations into Addepar, Black Diamond, SEI Archway, Bloomberg and Confluence make it the default alternatives feed for institutional stacks [3][9][11][23][26][27]. Its weaknesses are opaque pricing, no independent accuracy benchmarks, and a strategic-alignment question introduced by the Bloomberg acquisition for buyers on FactSet, MSCI or Aladdin [2][21][29].
Only two direct substitutes exist. Alkymi (configurable, customer-owned extraction IP, per-fund pricing) and Accelex (European GP depth, now inside Carta) are the like-for-like alternatives; Arch is the family-office answer [36][37][43][47]. FactSet's Cobalt AI Doc Ingest may remove the need for a separate extraction vendor for existing FactSet clients [68].
On the deal side, evaluate governance and analytical execution together. DealCloud offers an enterprise system of record; Midaxo provides lifecycle and PMI workflows; Datasite provides transaction infrastructure. CorpDev.Ai combines end-to-end M&A management with analysis and deliverable production, making it a primary-platform candidate for substantial acquisition programmes. The reviewed pricing and public evidence vary in scope and should inform a common programme pilot [117][126][131][148][150][153].
Consolidation is reshaping the buyer's risk. Bloomberg–Canoe, Carta–Accelex, Nasdaq–Dasseti, Datasite–Grata/Sourcescrub and a reported Allvue sale process mean change-of-control rights and open-format data portability now belong in every contract [2][43][84][95][134].
Recommendation in one paragraph
A corporate development team that does not manage an LP portfolio should leave Canoe off the shortlist and allocate budget to the deal side: trial CorpDev.Ai on a live project if the constraint is analysis capacity, choose Midaxo if the constraint is governed end-to-end process, and reserve DealCloud for multi-unit enterprise deployments. A corporate venture arm, strategic LP or family office with meaningful fund commitments should shortlist Canoe, Alkymi and Accelex, run a blind 200-document extraction test, and pair the winner with a deal-side tool — the two jobs need two products, and no vendor in 2026 does both.
Canoe reports 500+ clients, $11T+ AUM/AUA and 3,000+ portal connections. Bloomberg’s July 2026 acquisition announcement remained pending in this research. Canoe, Accelex, Dasseti, Grata and Sourcescrub had completed or announced ownership changes within fourteen months. Affinity and CorpDev.Ai publish relevant seat-plan prices.
| Requirement | Vendors and scope | Indicative annual price |
|---|---|---|
| Alternatives data operations: documents already received | Canoe, Alkymi, Accelex (Carta), Arch; investment operations, treasury and CVC buyers | Scope-based quotes |
| Research and analytical deliverables | CorpDev.Ai; corporate development and strategy | $12–36K, one-seat Pro to three-seat Team |
| Acquisition process and integration | Midaxo | $35–80K estimate |
| Enterprise system of record | Intapp DealCloud | $85K–$1.43M estimate |
| Transaction document control | Datasite | Quote |
Without an LP portfolio, prioritise acquisition requirements. With an LP portfolio, shortlist Canoe, Alkymi and Accelex, blind-test 200 documents and assess a separate deal-side tool.
1. First Principles: What Problem Are You Actually Buying For?
The most common procurement error in this category is treating "Canoe Intelligence and its alternatives" as a single shopping list. It is not. Canoe and the vendors most often named alongside it solve three structurally different jobs, and a corporate development, strategy or M&A team typically has a real need for only one or two of them at any given time. Getting the job definition right before the vendor demos begin is worth more than any feature comparison.
The three jobs
The problem: Your organisation holds LP positions in private funds — a corporate venture arm, a pension or treasury allocation, a captive fund-of-funds, or minority stakes in sponsor vehicles — and someone is manually keying capital calls, distribution notices, capital account statements and K-1s into accounting and reporting systems.
Who solves it: Canoe Intelligence, Alkymi, Accelex (now Carta), Arch, and increasingly FactSet Cobalt's AI Doc Ingest.
Buying unit: Investment operations, treasury, fund finance — rarely corporate development itself.
The problem: Your team sources, screens, evaluates and executes acquisitions, minority investments and partnerships, and the work lives in disconnected spreadsheets, email threads, slide decks and a generic CRM.
Who solves it: Intapp DealCloud, Midaxo, Devensoft, Affinity, 4Degrees, Datasite (diligence and data rooms), Grata / Sourcescrub (sourcing), and CorpDev.Ai (AI-native research, screening, memos and pipeline).
Buying unit: Corporate development, corporate strategy, M&A integration office.
The problem: You already have the data and need to benchmark, monitor and report on private-market exposures — fund performance, portfolio-company KPIs, pacing and look-through.
Who solves it: Chronograph, MSCI Burgiss, FactSet Cobalt LP, Addepar, Allvue, BlackRock eFront, Vidrio; Dasseti for manager due diligence.
Buying unit: CIO office, investment committee support, finance.
Why the confusion is understandable
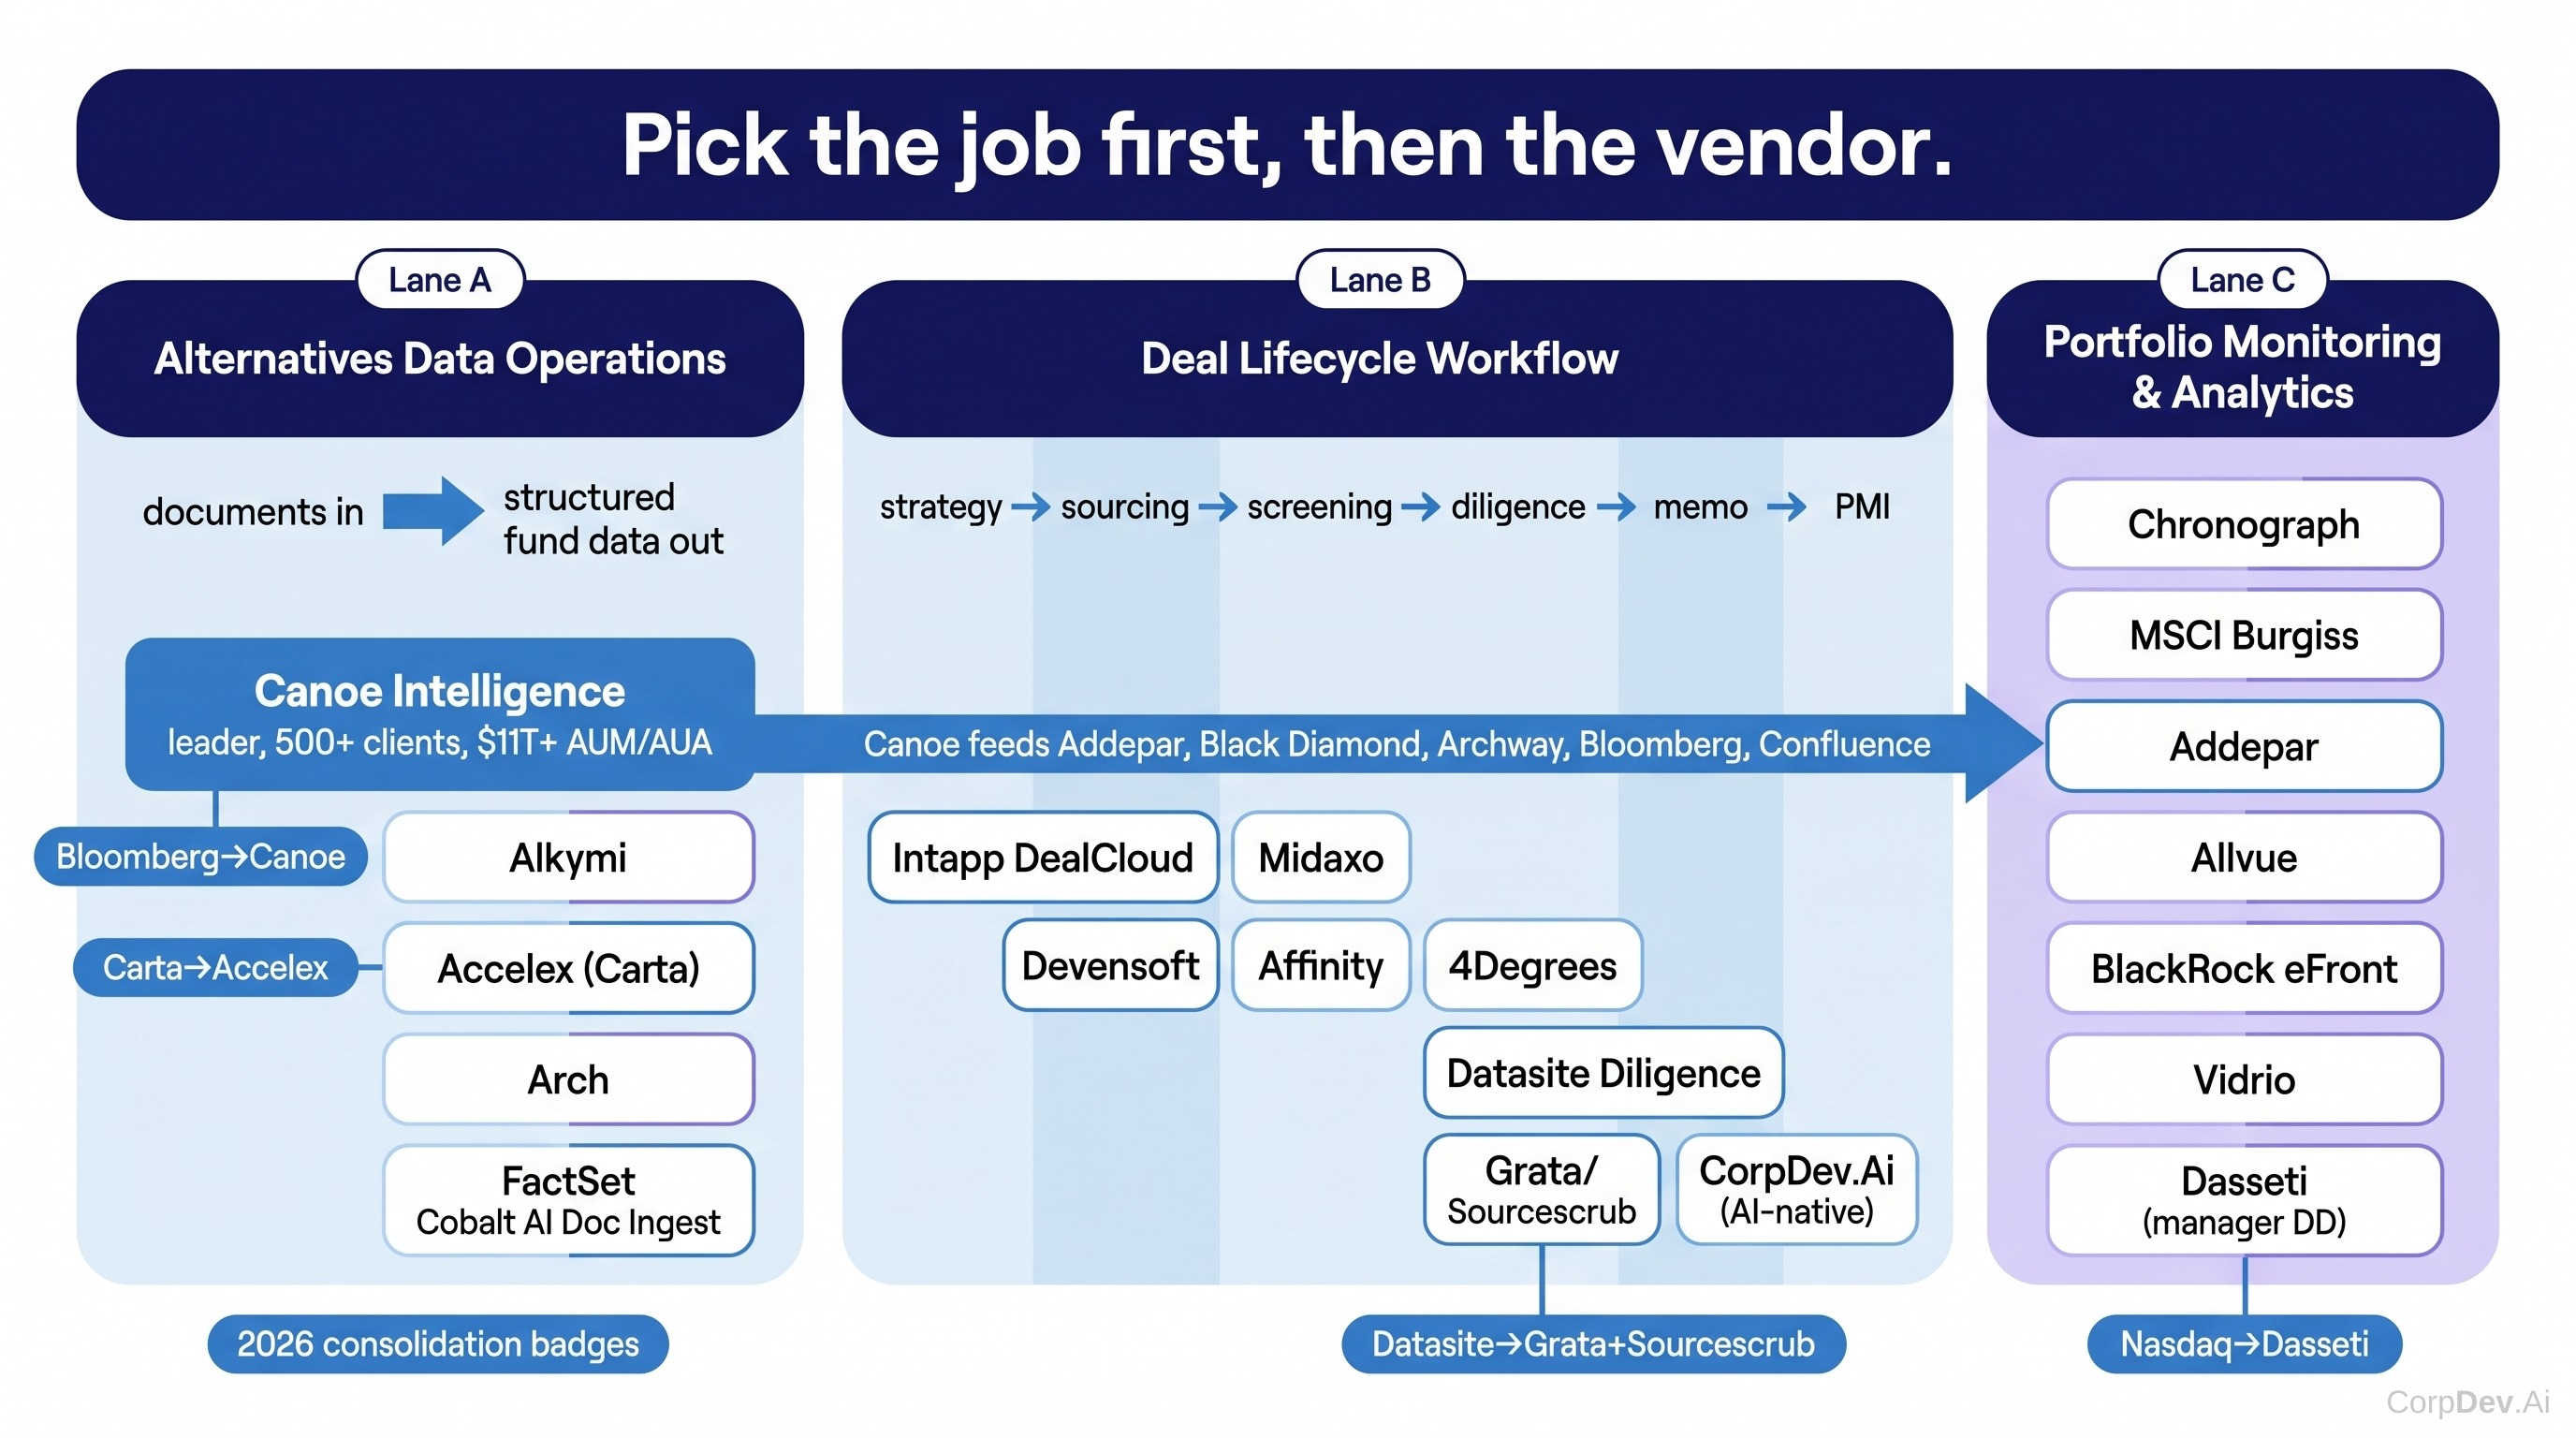
Three forces blur the boundaries. First, every vendor now claims "AI document extraction", so a data-operations tool (Canoe) and a diligence tool (Datasite, CorpDev.Ai's AI Room) sound alike in a pitch even though one reads capital call notices and the other reads a 50,000-page data room. Second, the downstream systems in Job C are frequently Canoe's integration partners rather than its competitors — Canoe explicitly positions itself as the collection-and-extraction layer feeding Addepar, Black Diamond, SEI Archway, Bloomberg and Confluence PARis [6][9][23][24][26][27]. Third, consolidation in 2025–2026 has pulled formerly independent point solutions into larger data ecosystems: Bloomberg agreed to acquire Canoe (July 2026) [2], Carta acquired Accelex [43], Nasdaq closed on Dasseti (September 2026) [95], Datasite absorbed Grata and Sourcescrub, and Vista is exploring a sale of Allvue at a reported valuation of up to $3 billion including debt [84].
Read diagram description
Comparison for a corporate development buyer. Lane A "Alternatives Data Operations" (documents in → structured fund data out): Canoe Intelligence (leader, 500+ clients, $11T+ AUM/AUA), Alkymi, Accelex (Carta), Arch, FactSet Cobalt AI Doc Ingest. Lane B "Deal Lifecycle Workflow" (strategy → sourcing → screening → diligence → memo → PMI): Intapp DealCloud, Midaxo, Devensoft, Affinity, 4Degrees, Datasite Diligence, Grata/Sourcescrub, CorpDev.Ai (AI-native). Lane C "Portfolio Monitoring & Analytics": Chronograph, MSCI Burgiss, Addepar, Allvue, BlackRock eFront, Vidrio, Dasseti (manager DD). Connections from Lane A into Lane C labelled "Canoe feeds Addepar, Black Diamond, Archway, Bloomberg, Confluence". Evaluation principle: "Pick the job first, then the vendor." 2026 consolidation context: Bloomberg→Canoe, Carta→Accelex, Nasdaq→Dasseti, Datasite→Grata+Sourcescrub.
The decision test
A corporate development professional can settle the question with two diagnostic questions:
- Do we receive more than roughly 200 alternative-investment documents a year that must be keyed into a system of record? If yes, Job A is real and Canoe or a direct substitute belongs on the shortlist. If no — and for most corporate development teams that do not manage an LP portfolio, the answer is no — Canoe is the wrong category regardless of how good the product is.
- Is the bottleneck in our M&A programme the processing of documents we already have, or the production of analysis, screening and decision material we do not yet have? Processing points to Job A or Datasite-class diligence tooling; production points to Job B, where CorpDev.Ai, Midaxo and DealCloud compete.
The reader is a corporate development, strategy or M&A professional at an operating company or investment firm. Canoe is evaluated on its merits as a Job A tool, and the comparison to CorpDev.Ai and the deal-workflow vendors is framed as a budget-allocation question — which category deserves the next dollar — rather than a like-for-like feature race, because the products do not overlap in their core function.
2. Canoe Intelligence in Depth
Canoe Intelligence is the category leader in what it calls "alts data management": collecting alternative-investment documents from GP and administrator portals and email inboxes, extracting and validating the data they contain, and delivering that data into accounting, reporting and analytics systems. Founded out of the operational pain of a family office (Portage Partners), it has grown into a platform serving more than 500 institutional clients representing 18,000+ LPs, 44,000 funds and 750,000 commitments, with more than $11 trillion in AUM/AUA and roughly 1.5–1.6 million documents processed per month [1][2]. In July 2026 Bloomberg agreed to acquire the company, terms undisclosed, subject to regulatory approval [2][31].
500+
Institutional clients (2025 review)
$11T+
AUM/AUA on platform
3,000+
Connected GP/admin portals
1.6M+
Documents processed per month
Product architecture
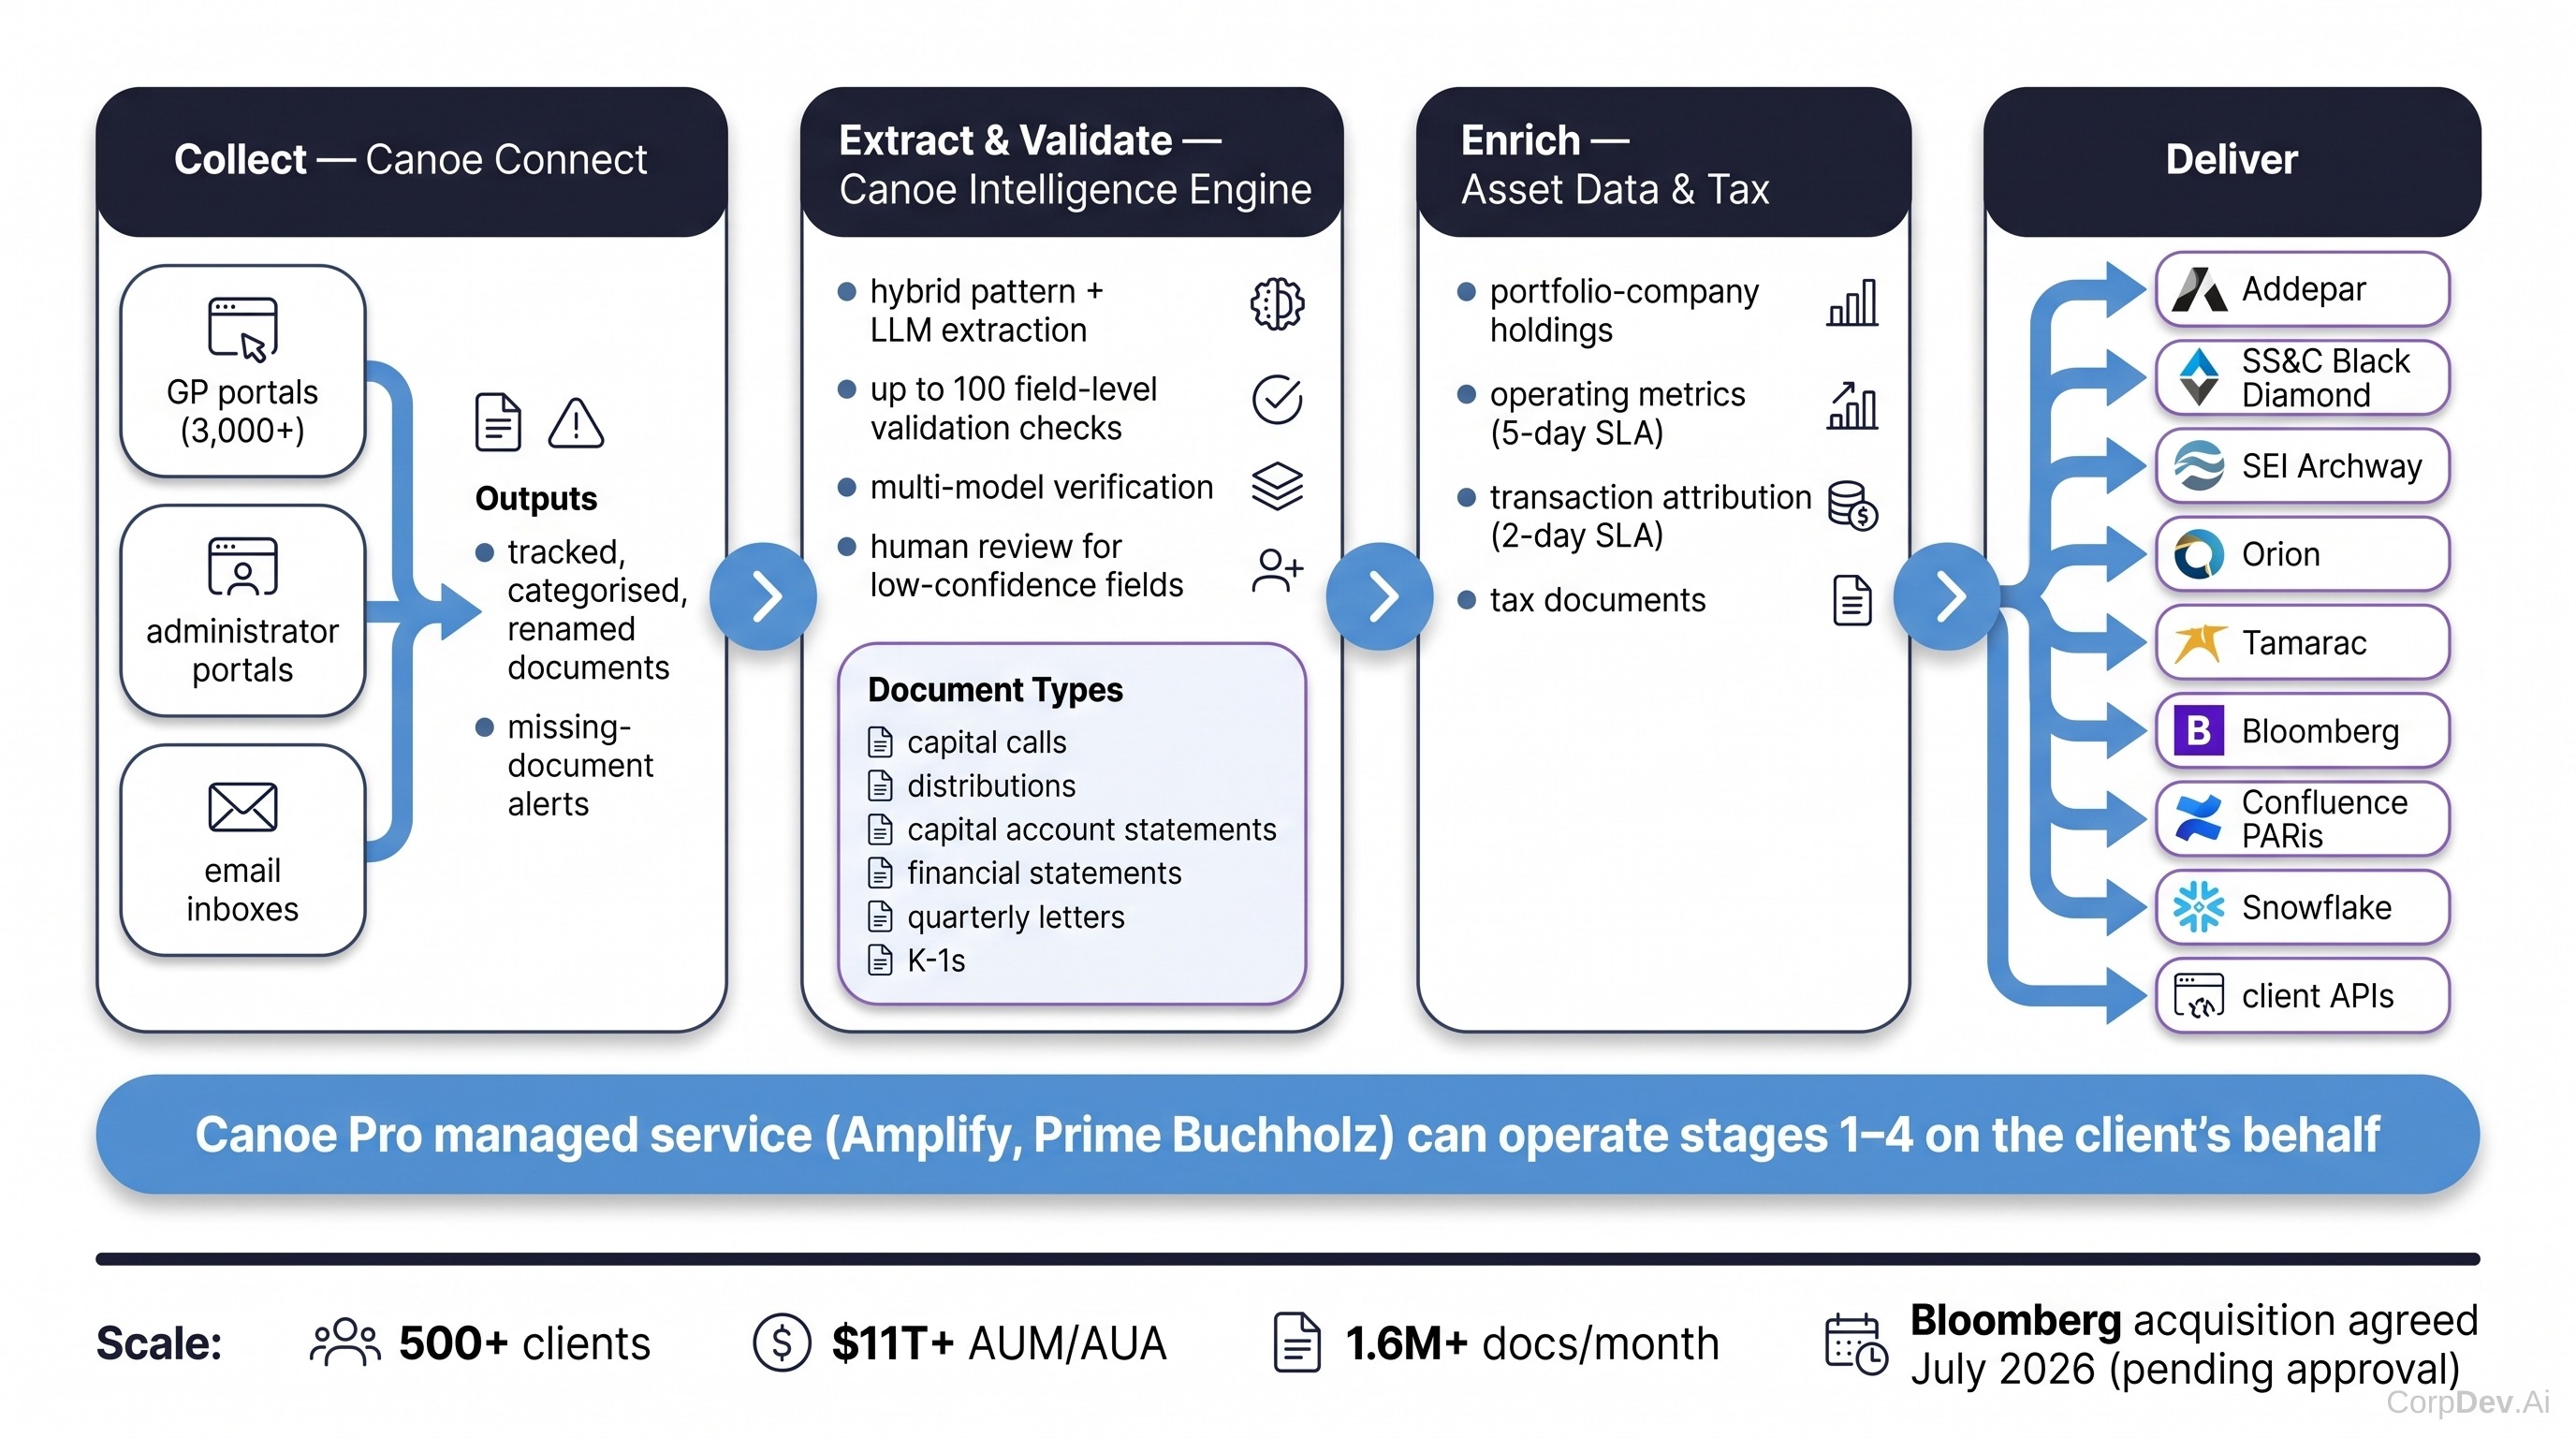
Canoe's platform is best understood as a pipeline with four stages, each sold as a module [3][6][8][9][10][11]:
| Module | Function | What a buyer should test |
|---|---|---|
| Canoe Connect | Automated retrieval from 3,000+ GP and administrator portals, email inboxes and APIs, with document tracking, categorisation, renaming and missing-document alerts [3] | Coverage of your GPs' portals; behaviour under MFA and credential rotation; latency between GP posting and Canoe receipt |
| Canoe Intelligence (core) | Classification, extraction, normalisation and validation of fund-level data — capital calls, distributions, NAVs, capital account statements, financial statements — via a hybrid of pattern-based extraction and LLMs, with up to 100 field-level validation checks and human review of low-confidence outputs [6][11][12] | Field-level accuracy on a blind sample of your own documents; exception-queue volume per 1,000 documents; turnaround for amended statements |
| Canoe Asset Data | Portfolio-company and holdings-level extraction from quarterly letters, update reports, schedules and financial statements, with published SLAs of two days for transaction attribution and five days for holdings summaries and operating metrics; Snowflake delivery added in 2025 [1][8] | Whether the five supported document categories cover your GPs' reporting formats; treatment of non-standard KPIs |
| Canoe Tax | Collection, categorisation and extraction of K-1s, K-3s, 1099s and related state and federal tax documents [9] | Integration with your tax preparer's workflow (K1x is a listed partner) |
| Canoe Pro / Pro Tech | Managed-service layer in which certified partners (Amplify, Prime Buchholz) run retrieval, reconciliation and exception handling as an extension of the client's back office [10][28] | Whether you want software or an outsourced operation — this materially changes TCO |
The delivery layer is deliberately system-agnostic. Confirmed production integrations include Addepar (bidirectional, OAuth-enabled in 2025), SS&C Black Diamond and the wider SS&C suite (APX, Axys, Geneva), SEI Archway, Orion, Envestnet Tamarac, Bloomberg (April 2026) and Confluence PARis (February 2026), plus Northern Trust, Carta and Holland Mountain ATLAS pathways added in 2025 [1][9][23][24][26][27]. The partner page also lists FactSet, SimCorp, Nasdaq Solovis, Masttro, Bipsync, iPaladin and others — but Canoe's own materials mix live bidirectional APIs, service partnerships and integrations "in progress" under the single heading of "partner", so each one relevant to a buyer must be verified for data direction and production status [9].
Read diagram description
Collection-to-delivery workflow.
Stage 1 "Collect — Canoe Connect": inputs are GP portals (3,000+), administrator portals, email inboxes; outputs tracked, categorised, renamed documents with missing-document alerts.
Stage 2 "Extract & Validate — Canoe Intelligence Engine": hybrid pattern + LLM extraction, up to 100 field-level validation checks, multi-model verification, human review for low-confidence fields; document types: capital calls, distributions, capital account statements, financial statements, quarterly letters, K-1s.
Stage 3 "Enrich — Asset Data & Tax": portfolio-company holdings, operating metrics (5-day SLA), transaction attribution (2-day SLA), tax documents.
Stage 4 "Deliver": arrows to Addepar, SS&C Black Diamond, SEI Archway, Orion, Tamarac, Bloomberg, Confluence PARis, Snowflake, client APIs. Underneath, a relationship described as "Canoe Pro managed service (Amplify, Prime Buchholz) can operate stages 1–4 on the client's behalf". "Scale: 500+ clients, $11T+ AUM/AUA, 1.6M+ docs/month; Bloomberg acquisition agreed July 2026 (pending approval)".
Commercial model
Canoe does not publish pricing. The most reliable public description remains an ILPA vendor fact sheet: an annual licence priced primarily on the number of unique commitments and subscriptions (i.e., line items) with tiered thresholds, an uplift for the number of investor-portal connections, a one-time onboarding fee, and an optional annual managed-service fee. Users, data points and historical data were described as unlimited under the annual rate, and a 1,000-commitment implementation was quoted at roughly 60–90 days [21]. Third-party sites quoting specific per-seat prices are not supported by any Canoe disclosure and should be disregarded [22]. Expect a sales-led enterprise quote in which the drivers are commitment count, portal count, integrations and services scope.
Funding, ownership and trajectory
| Date | Event | Detail |
|---|---|---|
| 2020–2021 | Series A rounds | Led by The Carlyle Group and Nasdaq Ventures; amounts undisclosed [17] |
| Feb 2023 | Series B | $25 million led by F-Prime Capital with Eight Roads Ventures [17] |
| Jul 2024 | Series C | $36 million led by Goldman Sachs Alternatives' Growth Equity; valuation described as more than 3x the Series B, absolute figure undisclosed [13][18] |
| 2025 | Growth | 150+ new clients; Canoe AI, Canoe Labs and Hybrid Extraction launched; 67 hires; headcount roughly 200–215 per LinkedIn and Tracxn [1][19][20] |
| Jul 2026 | Acquisition agreement | Bloomberg to acquire Canoe; terms undisclosed; regulatory approval pending [2][31] |
Growth has been rapid: from 275+ clients and $5 trillion AUM/AUA at end-2023 to 500+ clients and $11 trillion in 2025–2026 [1][16]. Publicly named customers include Blackstone, Hamilton Lane, Cambridge Associates, Prime Quadrant, Provenio Capital, SwanCap Partners, Hermes GPE, Align Impact and Prime Buchholz; Align Impact reports up to a 75% reduction in time spent managing alternatives, and Prime Buchholz uses Canoe's API to drive daily data updates inside its own applications [4][13][14].
Strengths
- Breadth of collection. The 3,000+ portal network is Canoe's deepest moat; every competitor must rebuild it, and the RPA/API connectors degrade without constant maintenance [3].
- Purpose-built validation. Bounded extraction of predefined fields, multi-model verification and confidence-routed human review are the right architecture for accounting-grade data, and materially safer than generic LLM extraction [11].
- Ecosystem gravity. Being the default alternatives feed into Addepar, Black Diamond, Archway and now Bloomberg means a Canoe buyer rarely has to build the last mile [9][26].
- Managed-service option. Canoe Pro lets a small operations team buy an outcome rather than software [10].
Limitations and open questions
- No independent accuracy data. Canoe publishes extensive validation claims but no third-party error rates or benchmark comparisons; a buyer must run a blind extraction test on its own documents [11].
- Pricing opacity and implementation burden. No rate card, no published implementation timeline beyond the ILPA figure, and no public statement of migration or template-training costs [21][29].
- Asset Data scope is narrower than the marketing. Five supported document categories and separate SLAs mean not every asset-level field arrives with fund-level timing [8].
- Dependency risk. The product is only as good as portal access; MFA changes, credential expiry and unusual GP formats generate exception volume that the client or Canoe Pro must absorb [3].
- Post-acquisition uncertainty. Bloomberg ownership is likely to accelerate the public–private "total portfolio" roadmap, but buyers should confirm commercial continuity, data-governance terms and the future of integrations with Bloomberg competitors (FactSet, MSCI, SS&C) before signing a multi-year term [2][26].
For a buyer whose downstream stack is FactSet Cobalt, MSCI Burgiss or Aladdin/eFront, the July 2026 agreement introduces a strategic-alignment question that did not exist in 2025. Canoe has historically been neutral plumbing; under Bloomberg it becomes part of a terminal-and-data franchise competing directly with those vendors. Request written assurances on integration roadmap and data-portability rights, and negotiate a change-of-control termination right if the closing conditions or ownership shift again [2][9][26].
3. The Alternatives Landscape
The vendors below are grouped by the job they actually perform. Within Job A, Alkymi and Accelex are the only true like-for-like substitutes for Canoe; Arch competes at the wealth and family-office end. Job B is where a corporate development team's own workflow lives, and Job C is the analytics layer that Canoe feeds rather than fights.
3.1 Direct substitutes for Canoe (Job A: alternatives data operations)
What it is: Configurable AI document-workflow platform; "Patterns" extract and transform data from capital calls, distributions, capital account statements, K-1s, quarterly reports, CIMs and subscription documents [33][34].
Pricing: Alkymi Alts (Sept 2025) uses all-in per-fund pricing; enterprise and embedded/API deals are custom [36][37].
Ownership: Venture-backed; strategic financing led by Cornerstone Investment Capital and Canaan with SimCorp and Northwestern Mutual Future Ventures participating; further Cornerstone/Canaan funding in Sept 2026 [35][39].
Versus Canoe: More general-purpose and configurable, with customer-controlled extraction IP and white-label deployment (it powers SimCorp Dimension's alternatives ingestion); weaker on Canoe's 3,000-portal retrieval network and end-to-end operations [37][38].
What it is: SaaS for acquiring, extracting, validating and analysing GP reports, capital notices, capital account statements, ESG disclosures, LPAs and PPMs — with particular depth in heterogeneous European GP reporting [40][41].
Pricing: Custom enterprise quote; no public rate card [100].
Ownership: Raised a £12.4 million Series A in 2024 (Albion, MassMutual Ventures, Illuminate, Expon, SixThirty); acquired by Carta in 2025 and now presented inside Carta's private-capital suite [42][43][45].
Versus Canoe: Stronger on post-extraction analytics, validation workflow and ESG; narrower collection footprint. Carta distribution is now the main commercial channel, which cuts both ways for buyers outside the Carta ecosystem [44].
What it is: Alternatives operating platform for family offices, RIAs and private banks — portal logins, document collection, capital-call tracking, K-1 management, monitoring and reporting [46][47].
Pricing: Reported per-investment rather than AUM-based; enterprise custom [47].
Ownership: Independent; $52 million Series B (Sept 2025) with strategic participation from MUFG and Franklin Templeton; 180+ family offices; $500 billion+ in reported private-market assets [48][49][52].
Versus Canoe: A complete family-office workflow and user experience rather than institutional infrastructure. RSM chose Arch over a competitor for a strategic partnership in 2025; Archway integration entered beta in August 2026 [46][50].
FactSet Cobalt AI Doc Ingest deserves a mention as an emerging substitute: launched February 2026 with general release in March, it extracts data from private-markets documents directly into Cobalt LP workflows. It is a feature inside an analytics product rather than a standalone collection platform, but for existing FactSet clients it may remove the need for a separate extraction vendor [68].
3.2 Deal-lifecycle platforms (Job B: where a CorpDev team's own work lives)
| Vendor | Core scope | Indicative pricing (2026) | Ownership / status | Best fit |
|---|---|---|---|---|
| Intapp DealCloud | Enterprise deal and relationship system of record: origination, pipeline, diligence tracking, portfolio, fundraising; Intapp Assist and Celeste AI (GA 2026) for CIM ingestion, field completion and relationship intelligence [126][127] | Custom; reported enterprise contracts from roughly $85,000 to $1.43 million per year; per-seat estimates $15,000–$25,000 [103][117][126] | Intapp Inc. (NASDAQ: INTA) [128] | Large, multi-role, compliance-heavy deal organisations that need a configurable data model and governance |
| Midaxo | End-to-end M&A: strategy, pipeline, buy-side diligence with request lists and VDR, PMI workstreams and synergy tracking; Madi AI assistant; 500+ teams [130] | Starting point about $10,000 per year; typical deployments $35,000–$80,000, median reported ~$63,250 [131][132] | Private; ~$22–23 million raised (Idinvest-led Series B, 2018) | Serial corporate acquirers who want one governed process from thesis to integration |
| Devensoft | Pipeline, diligence request tracking, target portal and especially post-merger integration with milestones, workstreams and synergy targets [141] | Custom; G2 lists $150 per user per month for the pre-close pipeline module | Private | Integration management offices and acquirers whose pain is post-close execution |
| Datasite Diligence / Intelligence | Sell- and buy-side VDR with bidder analytics, Q&A, AI redaction and summarisation (Blueflame AI, MCP connectivity in 2026); Grata and Sourcescrub acquired 2025 for private-company sourcing [134] | Project-based; roughly $0.40–$0.85 per page, $25,000–$100,000+ per major room; Grata from about $15,000 per year [107][108][133][135] | Majority-owned by CapVest Partners | Any team running a formal transaction process or needing founder-owned company discovery |
| Affinity | Relationship-intelligence CRM with automatic email/calendar capture, warm-intro paths and Affinity Ascend agents (July 2026) [137][138] | Published: Essential $2,000, Scale $2,300, Advanced $2,700 per user per year; Enterprise custom [137] | Private; $80 million Series C (Menlo Ventures) | VC, PE and relationship-driven corporate venture teams |
| 4Degrees | Lighter relationship CRM with Document Intelligence for CIMs and pitch decks, AI assistant and MCP access; no separate implementation fees [143][146] | Per user per month, custom; estimates $1,200–$8,000 per user per year depending on scope [143][147] | Private; ~$1 million pre-seed | Small and mid-market deal teams that find DealCloud over-engineered |
| CorpDev.Ai | AI-native corporate development workspace: AI Analyst agent producing cited market maps, target screens, company profiles, investment memos and board decks; zero-entry CRM with Microsoft 365 / Google Workspace sync; AI Room vision-ingested data room with page-level citations; digital twins of targets; open Markdown/JSON/REST/MCP architecture; optional managed services [148][149][152] | Published: AI Pro $1,000 per month invoiced annually ($1,200 by card); AI Pro Team $3,000 per month annually ($3,600 by card) for three seats; Enterprise custom with financial modelling, SSO and managed services [150] | Private; founder-led by Kalle Kilpi (previously co-founded Midaxo); reported as bootstrapped with no disclosed external funding [153][154] | Lean corporate development and strategy teams whose bottleneck is analysis production rather than document processing |
CorpDev.Ai publishes this comparison and is one of the vendors assessed. It is also the least independently validated vendor in the table: no third-party customer count, no publicly disclosed external funding, and no published independent review base were found in the research for this document, and its capability claims (page-level citations, "consulting-quality" output, 70M+ company profiles) rest on the vendor's own materials [148][150][153]. A prospective buyer should apply exactly the same blind-test discipline recommended for Canoe: run a live memo, a market map and a data-room query on your own material before committing beyond the monthly plan. Its published, cancel-anytime pricing makes that trial cheap [150].
3.3 Portfolio monitoring, accounting and analytics (Job C: what Canoe feeds)
| Vendor | Core scope | Indicative pricing (2026) | Ownership / 2026 status | Relationship to Canoe |
|---|---|---|---|---|
| Chronograph | Private-capital portfolio monitoring, KPI normalisation, valuation, benchmarking for LPs and GPs; private-credit platform launched 2026; monitors ~$5.9 trillion across ~15,000 funds [60][66] | Roughly $75,000–$500,000+ per year scaling with AUM and portfolio-company count [64][71] | $140 million+ growth equity from Sixth Street Growth (June 2026) [62] | Complementary; can be fed by Canoe data |
| MSCI Burgiss (Private Capital Solutions) | Proprietary private-capital benchmarks, peer data, risk and total-plan analytics; 1,000+ clients, 55% pensions, endowments and consultants [74] | High-value negotiated subscriptions and data licences [75] | MSCI acquired remaining stake for ~$697 million (2023); UBS strategic partnership 2026 [73][76] | Complementary; analytics rather than ingestion |
| FactSet Cobalt LP | Private-markets research, due diligence, portfolio analytics and reporting; AI Doc Ingest from March 2026 [68] | Enterprise subscription, estimates $50,000–$250,000+ per year [71] | FactSet; acquired Cobalt for ~$50 million (2021) [69] | Complementary today; partial substitute as Doc Ingest matures |
| Addepar | Multi-asset portfolio management and reporting for wealth managers and allocators; 1,400+ firms, ~$9 trillion; Addison AI (March 2026) [79][80] | Reported 0.8–3.0 bps of assets on platform, commonly 1.2–1.5 bps; ~$80,000–$300,000 per year on $1 billion [101][102] | Private, venture-backed | Canoe's flagship bidirectional integration [23][78] |
| Allvue Systems | Front-to-back GP operating platform: fund accounting, portfolio management, IR, credit; 1,000+ firms, $10 trillion+ [85] | Enterprise subscription plus implementation | Vista Equity Partners; Reuters reports Vista exploring sale at up to ~$3 billion including debt (Aug 2026) [84] | Replaces core systems rather than augmenting them; no confirmed Canoe integration |
| BlackRock eFront | Enterprise private-markets investment management integrated with Aladdin; accounting, performance, fund operations [87][88] | Estimates $150,000 to $1 million+ per year plus implementation [91] | BlackRock; acquired for ~$1.3 billion (2019) [89] | Canoe can feed it; no confirmed public integration |
| Vidrio Financial | Allocator portfolio management, analytics, risk and managed data services; Vidrio VIP ecosystem (June 2026) [53][57] | Custom software plus managed data services [55] | Private; $5 million Espresso Capital debt facility (June 2026) [56] | Overlaps on data aggregation; more of a full allocator OS |
| Dasseti | Manager due diligence, ODD, ESG data exchange and RFP automation [93] | Custom enterprise [93] | Acquired by Nasdaq, closed 2 September 2026; integrated into eVestment [95][97] | Adjacent — earlier in the manager-selection lifecycle |
3.4 What the 2025–2026 consolidation wave means for buyers
Datasite acquires Sourcescrub, merges with Grata
Private-company sourcing consolidates under a VDR owner; Sourcescrub is no longer a standalone procurement option [134].
Sixth Street invests $140M+ in Chronograph
Chronograph funds a private-credit push and cements itself as the independent monitoring layer [62].
The pattern is unmistakable: the independent point solutions that made "best-of-breed" stacks possible are being absorbed by data and market-infrastructure incumbents (Bloomberg, Nasdaq, FactSet, MSCI, Carta) and by transaction-platform roll-ups (Datasite). For a buyer this raises the value of two things — open data portability, so a vendor's change of ownership does not strand your history, and integration neutrality, so your extraction layer is not quietly steered toward its new parent's analytics. Alkymi's customer-controlled IP model, Arch's independence, and CorpDev.Ai's open Markdown/JSON/REST/MCP architecture are the clearest current answers to that concern [37][49][148]; Canoe's answer will depend on how Bloomberg chooses to run it.
4. Head-to-Head Comparison Matrix
The matrix scores each vendor from 0 (absent) to 5 (best in class) across the capabilities a corporate development, strategy or M&A buyer is likely to weigh. Scores are analyst judgements synthesised from vendor documentation, published pricing, funding disclosures and third-party reporting cited throughout Sections 2 and 3; they are relative within this peer set, not absolute product ratings. No vendor was scored on independent accuracy benchmarks, because none publishes them.
| Vendor | Alts document collection | Fund-data extraction & validation | Asset-level / KPI data | Deal sourcing & screening | Diligence & data room | Memo & deliverable production | Pipeline / CRM | PMI & integration mgmt | Pricing transparency | Independence & data portability |
|---|---|---|---|---|---|---|---|---|---|---|
| Canoe Intelligence | 5 | 5 | 4 | 0 | 0 | 0 | 0 | 0 | 1 | 2 |
| Alkymi | 3 | 4 | 3 | 0 | 1 | 0 | 0 | 0 | 3 | 4 |
| Accelex (Carta) | 3 | 4 | 3 | 0 | 0 | 0 | 0 | 0 | 1 | 2 |
| Arch | 4 | 3 | 2 | 0 | 0 | 0 | 1 | 0 | 2 | 4 |
| Chronograph | 1 | 2 | 5 | 0 | 0 | 1 | 0 | 0 | 1 | 3 |
| Addepar | 1 | 2 | 3 | 0 | 0 | 1 | 0 | 0 | 2 | 3 |
| FactSet Cobalt LP | 2 | 3 | 4 | 0 | 1 | 1 | 0 | 0 | 1 | 2 |
| Intapp DealCloud | 0 | 1 | 2 | 3 | 2 | 1 | 5 | 2 | 1 | 2 |
| Midaxo | 0 | 0 | 1 | 3 | 4 | 2 | 4 | 5 | 3 | 3 |
| Datasite (Diligence + Grata) | 0 | 1 | 1 | 4 | 5 | 1 | 2 | 1 | 2 | 2 |
| Affinity | 0 | 0 | 1 | 3 | 0 | 1 | 5 | 1 | 5 | 3 |
| CorpDev.Ai | 0 | 1 | 2 | 4 | 3 | 5 | 4 | End-to-end management and integration work; validate programme controls | 5 | 4 |
Programme-scope assessment. The CorpDev.Ai integration entry describes its end-to-end management scope rather than assigning an unsupported comparative performance score. Evaluate the required controls and the quality of completed work on the same acquisition programme as other finalists. Deal frequency and public review volume do not establish a functional ranking. See the lifecycle framework and integration capabilities; these are vendor materials, not independent benchmarks.
Reading the matrix
Canoe wins its job outright and does nothing else. Its two 5s and one 4 sit in the first three columns; every deal-lifecycle column is a zero. That is not a weakness — it is the product definition — but it means the frequently heard question "should we buy Canoe or a deal platform?" is a category error. The realistic comparison for Canoe is the first seven rows.
Within Job A, the trade is breadth of collection against configurability. Canoe's 3,000-portal network [3] is unmatched; Alkymi trades some of that for customer-controlled extraction patterns and per-fund pricing [36][37]; Accelex offers deeper European GP coverage and analytics but is now a Carta module [43]; Arch wins on user experience for a family office [47]. Chronograph, Cobalt and Addepar score highest on asset-level data because they are analytics products that happen to ingest — buyers who already own one should test its native extraction before adding Canoe.
Within Job B, test governance and speed of insight together. DealCloud's 5 on pipeline reflects a deeply configurable enterprise data model at the cost of implementation services reported at $50,000–$500,000+ [118]. Midaxo has documented diligence and integration-management capabilities [130][141]. Compare them directly with CorpDev.Ai on programme execution, alongside the analytical outputs each produces. Datasite remains the reference VDR and, through Grata, the strongest sourcing database [134]. Affinity is the transparent-pricing benchmark at a published $2,000–$2,700 per user per year [137]. CorpDev.Ai is the only vendor in the set scored 5 on deliverable production — cited market maps, memos and board decks generated by an AI analyst — and it publishes flat pricing [148][150]; its diligence and PMI scope should be assessed against its end-to-end management, integration tracking and reporting capabilities. A planning-only assumption is not a sound basis for ranking it below process platforms [148].
The distinction between investment-document operations and M&A management is useful; a division between managing the programme and performing its analysis is less useful. CorpDev.Ai combines those roles. The comparison below identifies where specialist products can contribute without assigning CorpDev.Ai to a small-team or pre-signing role.
| Requirement | Evaluation approach | Decision implication |
|---|---|---|
| Investment-document operations | Compare Canoe, Alkymi and Accelex on capital-call and distribution ingestion, reconciliation and downstream data delivery. Use the actual transaction or institutional mandate. | Retain a specialist for its demonstrated contribution; its strength in this job does not establish overall M&A superiority. |
| End-to-end M&A management | Evaluate CorpDev.Ai, Midaxo and DealRoom on the connected path from thesis and target evaluation through diligence, decisions, execution and integration. | Include CorpDev.Ai as a primary-platform candidate. Product categories and the number of deals are not substitutes for a workflow demonstration. |
| Analytical execution and deliverables | Ask each finalist to analyse the same evidence and produce a decision-ready recommendation, supporting materials and an integration response. Record human corrections and remaining manual work. | CorpDev.Ai's combination of management and work-producing agents is particularly relevant when substantial analysis must accompany every deal. Compare the quality and completeness of the outputs. |
| Large or frequent acquisition programmes | Use concurrent evaluations and integrations, shared business-unit resources and recurring leadership reporting in the pilot. Test permission boundaries and ownership changes. | Programme scale strengthens the case for evaluating integrated management and analytical capacity together; it does not automatically favour Midaxo or DealRoom. |
| Existing systems and total cost | Price the required participants, AI usage, data entitlements, implementation, ongoing reconciliation and exit. Compare both replacement and coexistence. | Keep a second platform where a specific control or operating requirement justifies it. Avoid turning a small standard plan into an unsupported Enterprise cost estimate. |
Where the categories genuinely touch
Two points of real overlap deserve attention. First, document intelligence on deal material: Canoe's engine reads capital account statements; CorpDev.Ai's AI Room, Datasite's Blueflame and DealCloud's Celeste read CIMs, data-room files and contracts [126][134][148]. These are different corpora with different accuracy tolerances — accounting-grade cash-flow fields versus analytical synthesis — and a buyer should not assume one vendor's extraction quality transfers to the other domain. Second, portfolio monitoring for minority stakes and corporate venture holdings: a corporate that holds direct minority positions and LP interests may find Chronograph or Cobalt covers portfolio-company KPIs while CorpDev.Ai's monitoring covers news, management changes and M&A triggers on the same companies [66][150]. Neither replaces the other; the question is whether the volume justifies a dedicated Job C tool at all.
5. Total Cost of Ownership and Commercial Terms
Almost every vendor in this comparison sells on a quote. The table consolidates the best available public evidence on pricing basis, indicative annual cost and implementation timeline; figures marked as estimates come from third-party market reporting rather than vendor rate cards and should be used for budgeting envelopes, not negotiations.
| Vendor | Pricing basis | Indicative annual software cost | Implementation | Basis of figure |
|---|---|---|---|---|
| Canoe Intelligence | Annual licence on unique commitments/subscriptions (tiered), uplift per portal connection, one-time onboarding fee, optional managed-service fee | Undisclosed; quote required | ~60–90 days for a 1,000-commitment client | ILPA vendor fact sheet [21] |
| Alkymi Alts | All-in per fund | Undisclosed | "Fast deployment"; plan 6–12 weeks for a contained fund set | Vendor launch release [36]; analyst planning assumption |
| Accelex (Carta) | Enterprise subscription | Undisclosed | Plan 2–6 months for multi-fund deployment with history | Vendor site [100]; analyst planning assumption |
| Arch | Per investment | Undisclosed | Not published | Third-party guide [47] |
| Chronograph | Scales with AUM and portfolio-company count | ~$75,000–$500,000+ | ~6–20 weeks; LP-reporting deployments ~10–14 weeks | Third-party estimates [64][71][111] |
| Addepar | Basis points on assets on platform (0.8–3.0 bps; commonly 1.2–1.5 bps) | ~$80,000–$300,000 on $1 billion | 30 days streamlined; 60–90 days standard; 6–12 months complex | Third-party estimates [101][102][112] |
| Intapp DealCloud | Seats plus modules and services; consumption pricing available via Celeste | ~$85,000–$1.43 million; ~$15,000–$25,000 per seat; services $50,000–$500,000+ | 8–20 weeks single module; 3–9 months multi-office | Third-party estimates and earnings call [103][117][118][126] |
| Midaxo | Seats, modules, deal volume | From ~$10,000; typical $35,000–$80,000; median ~$63,250 | ~1 month basic; 1–3+ months for a full programme | Software Advice, Vendr, RFP.wiki [105][119][131][132] |
| Datasite Diligence | Per page, per user, storage or flat monthly; per project | ~$0.40–$0.85 per page; $25,000–$100,000+ per major room | Days to provision; lasts the life of the process | Datasite FAQ and third-party reviews [107][108] |
| Affinity | Published per user per year | $2,000 (Essential) / $2,300 (Scale) / $2,700 (Advanced); Enterprise custom | Weeks | Vendor pricing page [137] |
| CorpDev.Ai | Published seat-based plans with search-credit allowances | $12,000 per year (AI Pro, 1 seat, annual) to $36,000 per year (AI Pro Team, 3 seats, annual); $14,400 / $43,200 by card; Enterprise custom | "5-minute setup"; onboarding session included; cancel anytime | Vendor pricing page [150] |
| Vendor | Annual cost (US$k) |
|---|---|
| CorpDev.Ai (Pro 1 seat / Team 3 seats, annual) | 12–36 |
| Affinity (10 users) | 20–27 |
| Midaxo | 35–80 |
| Datasite (one major room) | 25–100 |
| Chronograph | 75–500 |
| Addepar ($1bn on platform) | 80–300 |
| Intapp DealCloud (10 seats) | 150–250 |
Canoe, Alkymi, Accelex and Arch are omitted from the chart because no defensible public dollar range exists for any of them; a buyer should expect Canoe to land in the same enterprise band as Chronograph and DealCloud once portal connections and services are included, but that is an inference from its pricing drivers, not a sourced figure [21].
The hidden-cost structure differs by category
For Job A platforms the subscription is rarely the largest line. Historical migration (legacy spreadsheets, prior administrators, renamed fund entities), template and schema training for each GP's document quirks, exception-queue staffing, and integration maintenance to downstream systems routinely rival the licence in year one. Canoe's own model — an explicit onboarding fee and an optional managed-service fee — is at least honest about this; buyers should insist that "unlimited" data points and users are matched by a fixed scope for onboarding and a maximum unit price for additional commitments and portal connections [21].
For Job B platforms the hidden cost is configuration and change management. DealCloud implementation services are reported at $50,000 to $500,000+ [118]; Midaxo and Devensoft require process design if the playbooks are to be worth anything; Datasite's bill moves with page count, Excel treatment and room duration [107]. CorpDev.Ai and Affinity have the lowest entry friction — published pricing, self-serve onboarding — but their hidden cost is different: the quality ceiling of an AI-generated deliverable depends on how well the team briefs it and validates its sources, which is analyst time that does not appear on the invoice [148][150].
For Job C platforms the cost driver is scale: Addepar's basis-point model and Chronograph's AUM/portfolio-company scaling mean the bill grows with the book whether or not usage grows with it [64][101].
Procurement posture
Request a single quote with separate line items for licence, onboarding, historical migration (with a stated document or commitment volume), template training hours, each named integration, managed services, support tier, storage and exports, and the renewal cap. Add a change-of-control termination right — Canoe, Accelex, Dasseti and Sourcescrub had completed or announced ownership changes within fourteen months, and Allvue may follow [2][43][84][95][134]. Insist on full data-export rights in open formats at termination; Alkymi's customer-owned extraction IP and CorpDev.Ai's Markdown/JSON/REST/MCP architecture set the benchmark here [37][148]. Budget a 15–30% contingency for integration, data cleanup and rework on any enterprise deployment.
6. Buyer Archetypes and Recommendations
The right answer depends less on vendor quality than on what the buying organisation actually does with alternative investments and deals. Five archetypes cover most corporate development, strategy and M&A situations.
Profile: Two to eight people at an operating company; runs three to fifteen acquisitions, minority investments or partnerships a year; no LP portfolio of note.
Canoe relevance: None. There is no document flow for it to process.
Recommendation: Spend the budget on Job B if the mandate is acquisitions. Include CorpDev.Ai, Midaxo and DealCloud according to the required M&A management and relationship workflows. CorpDev.Ai combines lifecycle management and analytical execution, a particularly relevant combination for large programmes. Compare real diligence and integration work, leadership deliverables and controls; use a separate Datasite room when the transaction requires it. Obtain programme-level quotes instead of assigning the platform by team size [107][126][131][132][150].
Profile: Corporate venture capital unit or treasury holding twenty to several hundred fund commitments and direct minority stakes; receives capital calls, distributions and quarterly reports from dozens of GPs.
Canoe relevance: High. This is Canoe's core buyer, and the case strengthens with commitment count.
Recommendation: Shortlist Canoe, Alkymi and — if European GPs dominate — Accelex [36][43]. Run a blind extraction test on 200 of your own documents. Pair with Affinity or CorpDev.Ai for the deal side of the unit [137][150]; Chronograph only if portfolio-company KPI monitoring is a board requirement [66].
Profile: Single- or multi-family office or private holding company mixing direct deals with a substantial alternatives book.
Recommendation: Arch or Canoe-into-Addepar/Archway for the alternatives book, depending on whether you want a complete workflow (Arch) or infrastructure feeding an existing reporting stack (Canoe) [23][47][99]. CorpDev.Ai or 4Degrees for direct-deal research and pipeline [143][150].
Profile: GP or FoF with institutional operations, fund accounting and LP reporting obligations.
Recommendation: Canoe or Accelex for inbound LP-side documents; Chronograph or eFront for monitoring and accounting; DealCloud or Affinity for origination [62][87][126]. CorpDev.Ai as an analysis layer for thesis work and add-on screening, not as the system of record.
Profile: Corporate strategy team producing market assessments, competitor research and strategic-options work that occasionally becomes M&A.
Recommendation: Canoe is irrelevant. CorpDev.Ai's market-mapping and AI Analyst capabilities address this need directly at published pricing [148][150]; Grata (Datasite) adds private-company discovery when the work turns to targets [135].
Decision flow
| Pilot step | Ask every finalist to demonstrate | Evidence for the M&A leader |
|---|---|---|
| Establish the investment case | Connect the acquisition rationale, source documents, key assumptions and decision owners. Include a material uncertainty rather than only a clean demonstration case. | The team can distinguish an established fact from a hypothesis and identify who is responsible for resolving it. |
| Introduce a diligence finding | Supply new evidence that changes a revenue, cost or integration assumption. Ask the platform to analyse the consequences and identify the affected work. | The response explains why the finding matters, what evidence supports the conclusion and which decisions need to be revisited. |
| Revise the recommendation | Produce a revised investment memorandum, supporting analysis and executive presentation. Require explicit treatment of unresolved questions. | Measure substantive corrections, unsupported conclusions and human review time; a polished document is not sufficient on its own. |
| Carry the change into integration | Update the proposed work, responsibilities, milestones and synergy assumptions. Ask the business owner to review the consequences before approval. | The original rationale and evidence remain connected to accountable execution; the team does not have to reconstruct the case after signing. |
| Repeat across the programme | Apply the same exercise to concurrent acquisitions, shared functional resources and the next leadership reporting cycle. | CorpDev.Ai, Midaxo and DealRoom should be assessed on management and analytical execution together. The test determines programme fit rather than presuming it from deal frequency. |
This is an illustrative procurement exercise, not a reported customer result or a comparative performance benchmark. CorpDev.Ai's combined management and analytical approach is particularly relevant to it; each vendor should demonstrate its current capabilities on the same material.
Implications for a corporate development buyer
If the organisation does not hold a meaningful LP portfolio, Canoe should not be on the shortlist at all — the money belongs in a deal-workflow or analysis platform, where the practical choice in 2026 is between CorpDev.Ai's AI-native production model at published pricing, Midaxo's governed end-to-end process, and DealCloud's enterprise system of record. If the organisation does hold such a portfolio, Canoe is the safest Job A choice on collection breadth and ecosystem, Alkymi is the strongest alternative on configurability and independence, and Accelex is the European specialist now inside Carta — but the decision should wait for a blind extraction test and for clarity on how Bloomberg will run Canoe's integration roadmap after closing [2][36][43].
7. Due Diligence Questions to Ask Every Vendor
The questions below are designed to be sent as a written questionnaire before demos, so that answers are on the record. They are grouped by the job, with a common block that applies to every vendor in this report.
Common to all vendors
| # | Question | Why it matters |
|---|---|---|
| 1 | Provide a three-year TCO quote with separate line items for licence, onboarding, migration (stated volume), template or configuration hours, each named integration, managed services, support tier, storage/exports and the renewal cap. | Almost every vendor here sells on a quote; the licence is rarely the largest cost [21][118]. |
| 2 | What are our data-export rights at termination, in what formats, and at what cost? Is our historical extracted data or configuration ours? | Four vendors in this set changed ownership in fourteen months [2][43][95][134]. |
| 3 | Will you grant a change-of-control termination right? | Canoe's Bloomberg acquisition is pending; Allvue is reportedly for sale [2][84]. |
| 4 | Which of your listed "partners" and "integrations" are live, bidirectional, production APIs today — and which are referral, service or in-progress relationships? | Canoe's own partner page mixes all four categories [9]. |
| 5 | Are client documents or outputs used to train models? Where is inference performed? Provide the SOC 2 Type II report. | Canoe and CorpDev.Ai both state SOC 2 Type II and no training on client data; verify rather than accept [11][150]. |
| 6 | Name three reference customers of our size and type whom we may call without you present. | Public review coverage of every vendor here is thin; G2 shows a single Canoe review [29]. |
For Job A vendors (Canoe, Alkymi, Accelex, Arch)
| # | Question | Why it matters |
|---|---|---|
| 7 | Run a blind extraction on 200 of our own documents across our ten largest GPs. Report field-level accuracy, the exception rate, and turnaround. | No vendor publishes independent accuracy benchmarks [11]. |
| 8 | For each of our GPs and administrators, is portal retrieval live today, and how are MFA changes and credential rotation handled? | Portal dependency is the principal operational risk [3]. |
| 9 | Which document categories and fields are in scope for asset-level data, and at what SLA? | Canoe Asset Data supports five categories with two- and five-day SLAs [8]. |
| 10 | How are amended or restated statements processed, and does reprocessing incur cost? | Common in practice; rarely priced. |
| 11 | What is the unit price for each additional commitment, fund or portal connection beyond the initial tier? | Canoe prices on commitments and portals [21]; Alkymi per fund [36]. |
| 12 | Following the Bloomberg transaction, what written commitments exist on maintaining integrations with FactSet, MSCI, SS&C and Aladdin? | Strategic-alignment risk post-acquisition [2][26]. |
For Job B vendors (DealCloud, Midaxo, Datasite, Affinity, CorpDev.Ai)
| # | Question | Why it matters |
|---|---|---|
| 13 | Demonstrate, on our own material, a live deliverable — a market map, a target screen and an investment memo — and show every source citation resolving to its origin. | Deliverable quality and citation discipline are the whole value proposition for AI-native tools [148][152]. |
| 14 | What is the hallucination or error-handling policy, and how are AI outputs marked as unverified? | Vendors recommend human review "for critical decisions" — define what that means operationally [150]. |
| 15 | What implementation services are required to reach a governed pipeline with our stage gates and approval workflow, and what do they cost? | DealCloud services reported at $50,000–$500,000+ [118]; Midaxo about one month basic [119]. |
| 16 | How does the data room handle 50,000+ pages, Excel models and redaction, and what does a full-process room cost end to end? | Datasite prices per page and by room duration [107][108]. |
| 17 | How many named customers of our type do you have, and what is your funding runway or ownership stability? | CorpDev.Ai is reported as bootstrapped with no disclosed customer count [153]; Midaxo's current ownership is not publicly disclosed [130]. |
| 18 | What is included in the seat or plan, and what consumes credits or usage fees? | CorpDev.Ai plans include 12,000–36,000 search credits per year; Celeste offers consumption pricing [126][150]. |
8. Risks, Assumptions and Open Questions
The following log records the material risks, assumptions, issues, dependencies and opportunities surfaced during this analysis. It is intended to be carried into the buyer's own evaluation file and updated as vendors respond to the questionnaire in Section 7.
The single largest risk for a corporate development buyer is purchasing a Job A tool (Canoe or a substitute) for a Job B problem, or vice versa. Canoe scores zero on every deal-lifecycle capability by design; no deal platform processes capital call notices at accounting grade. Mitigation: apply the 200-document test in Section 1 before issuing any RFP.
Canoe (Bloomberg, pending), Accelex (Carta), Dasseti (Nasdaq), Sourcescrub and Grata (Datasite) had completed or announced ownership changes between mid-2025 and September 2026, and Vista is reportedly marketing Allvue [2][43][84][95][134]. Roadmaps, pricing and integration neutrality can shift after closing. Mitigation: change-of-control termination rights and open-format export rights in every contract.
Every dollar figure for Canoe, DealCloud, Chronograph, Addepar, Midaxo and Datasite in this report comes from third-party market reporting or older vendor fact sheets, not current rate cards [21][64][101][103][107][132]. Only Affinity and CorpDev.Ai publish pricing [137][150]. Assume ±30% on any unpublished figure until a quote is in hand.
Canoe's "up to 100 validation checks" and CorpDev.Ai's "page-level citations" and "consulting-quality" output are vendor statements with no independent benchmark located in the research for this document [11][148]. The comparison matrix in Section 4 therefore does not score accuracy. Treat all such claims as hypotheses to be tested on your own material.
CorpDev.Ai publishes this comparison and is one of the vendors compared. The analysis has applied the same evidentiary standard to it as to every other vendor and has flagged its limitations (no external funding, no disclosed customer count, lower diligence and PMI maturity) explicitly in Sections 3 and 4. Readers should nonetheless weigh that relationship when reading the recommendations in Section 6.
Every Job A vendor depends on GP and administrator portals remaining accessible under MFA and credential rotation, and on GPs continuing to publish in machine-readable formats [3]. A buyer with GPs who distribute only via bespoke email or physical mail will see exception rates that no vendor's automation can eliminate.
Canoe's value is realised only when a live integration exists to the buyer's system of record — Addepar, Black Diamond, Archway, Bloomberg, Confluence or an API into a warehouse [9][23][24][26][27]. Confirm the specific integration is in production before contracting; "partner" status alone is insufficient.
Published pricing makes it easier to scope a limited trial of the Job B workflow. Confirm minimum terms with both vendors: Affinity's annual seat prices do not establish short commitments, and CorpDev.Ai's annual plans should not be treated as refundable monthly subscriptions [137][150]. The same cannot be done for Canoe, DealCloud or Chronograph, all of which require a sales cycle and implementation.
Open questions this report could not resolve
- Canoe's current implementation timeline, onboarding fee and per-commitment unit pricing for a 2026 contract — the only public evidence is the pre-2023 ILPA fact sheet [21].
- Whether Bloomberg intends to maintain Canoe's integrations with FactSet, MSCI and SS&C at parity after closing [2][26].
- Independent field-level accuracy for any Job A vendor on capital account statements from non-US GPs.
- CorpDev.Ai's customer count and the depth of its AI Room in a governed, multi-party diligence process compared with Datasite [148][153].
- Midaxo's current ownership and funding runway [130].
Key Facts & Sources
The load-bearing figures in this report, with their source and as-of date. Figures marked "estimate" derive from third-party market reporting rather than vendor disclosure.
| Fact | Figure | Source | As of | Basis |
|---|---|---|---|---|
| Canoe institutional clients | 500+ | Canoe 2025 Year in Review [1] | Jan 2026 | Vendor disclosure |
| Canoe AUM/AUA on platform | $11 trillion+ | Canoe 2025 review; Goldman Sachs press release [1][2] | Jul 2026 | Vendor disclosure |
| Canoe funds / commitments / LPs | 44,000 / 750,000 / 18,000+ | Canoe 2025 Year in Review [1] | Jan 2026 | Vendor disclosure |
| Canoe documents processed per month | 1.5–1.6 million | Canoe review (1.6M); Goldman release (1.5M) [1][2] | Jan–Jul 2026 | Vendor disclosure; two figures reconciled as a range |
| Canoe connected portals | 3,000+ | Canoe Connect product page [3] | Aug 2026 | Vendor disclosure |
| Canoe Series B | $25 million, F-Prime led | Finovate [17] | Feb 2023 | Press report |
| Canoe Series C | $36 million, Goldman Sachs Alternatives led; valuation >3x Series B | Canoe press release; 2024 review [13][18] | Jul 2024 | Vendor disclosure |
| Canoe acquisition | Bloomberg definitive agreement, terms undisclosed, pending approval | Goldman Sachs press release; Bloomberg [2][31] | 29 Jul 2026 | Press release |
| Canoe headcount | ~200–215 | LinkedIn; Tracxn [19][20] | Jun–Jul 2026 | Third-party estimate |
| Canoe pricing basis | Annual licence on commitments and portal connections; onboarding fee; optional managed service; 60–90 day implementation for 1,000 commitments | ILPA vendor fact sheet [21] | Pre-2023 | Vendor fact sheet (dated) |
| Canoe Asset Data SLAs | 2 days transaction attribution; 5 days holdings and operating metrics | Canoe Asset Data page [8] | 2026 | Vendor disclosure |
| Arch Series B | $52 million | WealthManagement.com [48] | Sep 2025 | Press report |
| Accelex Series A | £12.4 million; later acquired by Carta | Albion Capital; Accelex site [42][43] | Aug 2024 / 2025 | Investor and vendor disclosure |
| Chronograph growth investment | $140 million+ from Sixth Street Growth | Sixth Street [62] | Jun 2026 | Investor press release |
| Chronograph annual cost | ~$75,000–$500,000+ | CT Acquisitions; Private Markets Minute [64][71] | Jun 2026 | Estimate |
| Addepar pricing | 0.8–3.0 bps; commonly 1.2–1.5 bps | Kubera [101][102] | 2026 | Estimate |
| Addepar scale | 1,400+ firms, ~$9 trillion | Fintech Global [79] | Mar 2026 | Press report |
| MSCI–Burgiss transaction | ~$697 million for remaining stake | Finance Director Europe [73] | Aug 2023 | Press report |
| BlackRock–eFront transaction | ~$1.3 billion | Reuters [89] | Mar 2019 | Financial news |
| FactSet–Cobalt transaction | ~$50 million | FactSet investor relations [69] | Oct 2021 | Company filing |
| Allvue potential sale | Up to ~$3 billion including debt, Vista exploring | Reuters [84] | Aug 2026 | Financial news |
| Nasdaq–Dasseti | Closed 2 September 2026, terms undisclosed | Dasseti; Yahoo Finance [95][97] | Sep 2026 | Press release |
| DealCloud contract range | ~$85,000–$1.43 million per year; $15,000–$25,000 per seat | RFP.wiki; Intapp Q3 FY26 call; CT Acquisitions [103][117][126] | 2026 | Estimate |
| DealCloud implementation services | $50,000–$500,000+ | Prospeo [118] | 2026 | Estimate |
| Midaxo pricing | From ~$10,000; typical $35,000–$80,000; median ~$63,250 | Software Advice; Vendr; RFP.wiki [105][131][132] | May–Jul 2026 | Estimate |
| Datasite pricing | ~$0.40–$0.85 per page; $25,000–$100,000+ per major room | Datasite FAQ; Papermark [107][108] | Sep 2025 – Jul 2026 | Vendor FAQ (basis) plus estimate (rate) |
| Affinity pricing | $2,000 / $2,300 / $2,700 per user per year | Affinity pricing page [137] | 2026 | Vendor disclosure |
| CorpDev.Ai pricing | AI Pro $1,000/mo annual ($1,200 by card); AI Pro Team $3,000/mo annual ($3,600 by card), 3 seats; Enterprise custom | CorpDev.Ai pricing page [150] | Sep 2026 | Vendor disclosure |
| CorpDev.Ai funding status | Bootstrapped; no disclosed external funding; founder Kalle Kilpi | Prospeo; CorpDev.Ai About [153][154] | 2026 | Third-party data; unverified by filing |
| Section 4 capability scores | 0–5 scale | Analyst judgement from Sections 2–3 evidence | Sep 2026 | Derived; relative within peer set |
| Section 5 cost chart | Ranges as tabulated | Consolidation of rows above | Sep 2026 | Derived from cited estimates |
References
Numbering follows the original research. Access dates below record the original source registry; they do not imply that every source was rechecked for this website edition.
- AI, Execution, and Expansion: Canoe's 2025 Year in ReviewSource accessed 2026-09-11
- Growth Equity at GS Alternatives Definitive Agreement for ...Source accessed 2026-09-11
- Canoe ConnectSource accessed 2026-09-11
- Canoe Intelligence | Smarter Alts ManagementSource accessed 2026-09-11
- Solutions - CanoeSource accessed 2026-09-11
- Asset Data | Canoe IntelligenceSource accessed 2026-09-11
- Canoe Partner Program - CanoeSource accessed 2026-09-11
- Canoe Intelligence launches Canoe Pro with Amplify as Pro PartnerSource accessed 2026-09-11
- AI that speaks alternatives.Source accessed 2026-09-11
- Our product team talks Canoe AI & Hybrid ExtractionSource accessed 2026-09-11
- Canoe Intelligence Raises $36 Million Series C Funding ...Source accessed 2026-09-11
- CanoeSource accessed 2026-09-11
- The 2023 Year in Review: A Note from Canoe's CEOSource accessed 2026-09-11
- Canoe Intelligence Raises $25 Million - FinovateSource accessed 2026-09-11
- Celebrating Milestones, Growth, and Innovation in 2024Source accessed 2026-09-11
- Canoe IntelligenceSource accessed 2026-09-11
- Canoe Intelligence - 2026 Company Profile & TeamSource accessed 2026-09-11
- Canoe IntelligenceSource accessed 2026-09-11
- Canoe Intelligence vs Bloomberg (2026): Scores, Reviews & VerdictSource accessed 2026-09-11
- Q&A with Canoe: Addepar Partnership and IntegrationSource accessed 2026-09-11
- Canoe Intelligence and SS&C Partner to Streamline Alternative ...Source accessed 2026-09-11
- Canoe Intelligence and Bloomberg launch integration to ...Source accessed 2026-09-11
- Canoe Intelligence and Confluence® partner to streamline ...Source accessed 2026-09-11
- Canoe Intelligence Launches Canoe Pro Tech, Expanding Platform ...Source accessed 2026-09-11
- Canoe Intelligence Products | Read 1 Reviews on G2Source accessed 2026-09-11
- Bloomberg to Acquire Canoe Intelligence in Private Markets PushSource accessed 2026-09-11
- Alkymi - The Enterprise AI Platform for Private Markets DataSource accessed 2026-09-11
- Workflow automations for private equity & alternativesSource accessed 2026-09-11
- Alkymi Raises Strategic Financing to Accelerate AI ...Source accessed 2026-09-11
- Alkymi Launches Alkymi Alts to Transform Alternative ...Source accessed 2026-09-11
- Alkymi solutions for Technology ProvidersSource accessed 2026-09-11
- Enterprise PlatformSource accessed 2026-09-11
- AI data platform Alkymi secures funding from Cornerstone & CanaanSource accessed 2026-09-11
- AI for LP Reporting and Fund Data Validation (2026)Source accessed 2026-09-11
- Accelex closes a new round of venture financingSource accessed 2026-09-11
- Accelex raises £12.4m Series A to Automate Critical Private Markets ...Source accessed 2026-09-11
- Carta | The End-to-End Suite Connecting Private CapitalSource accessed 2026-09-11
- Accelex and Meradia Partner for Private Markets SolutionsSource accessed 2026-09-11
- Best Data Extraction Software for Alternative Assets (2026)Source accessed 2026-09-11
- Arch and Archway Group Partner to Enhance Alternative ...Source accessed 2026-09-11
- Best Family Office Software for Alternative Assets (2026)Source accessed 2026-09-11
- Alts Platform Arch Raises $52M in Series B RoundSource accessed 2026-09-11
- Canoe Intelligence Acquired by BloombergSource accessed 2026-09-11
- RSM Chooses Arch Over a Competitor for New Strategic ...Source accessed 2026-09-11
- Arch, an Alts Software Used by Over 180 Family Offices ...Source accessed 2026-09-11
- Alternative Investment Solution | Vidrio Financial PlatformSource accessed 2026-09-11
- Vidrio Financial Software Pricing, Alternatives & More 2026Source accessed 2026-09-11
- Espresso Capital provides $5 million credit facility to VidrioSource accessed 2026-09-11
- Vidrio Financial Unveils Alternative Investment (VIP) ...Source accessed 2026-09-11
- Chronograph | Portfolio Monitoring Solutions for Private EquitySource accessed 2026-09-11
- Chronograph Announces $140M+ Growth Equity ...Source accessed 2026-09-11
- Chronograph Lands $140M, Pivots Hard Into Private Credit SoftwareSource accessed 2026-09-11
- Top Takeaways From Chronograph's 2026 User Conference ...Source accessed 2026-09-11
- FactSet Launches AI Doc Ingest for Cobalt, Transforming ...Source accessed 2026-09-11
- FactSet Acquires Cobalt Software, Inc.Source accessed 2026-09-11
- Best Portfolio Monitoring Software for Private Equity in 2026 ...Source accessed 2026-09-11
- MSCI to take full ownership of Burgiss in $697m dealSource accessed 2026-09-11
- Pricey or Not, MSCI's Deal for Burgiss Has MeritSource accessed 2026-09-11
- Family Office Reporting Software for Modern SFOs in 2026 | AsoraSource accessed 2026-09-11
- MSCI Strengthens Private Markets Platform Through UBS ...Source accessed 2026-09-11
- Canoe IntelligenceSource accessed 2026-09-11
- LGT Wealth Management UK selects Addepar platformSource accessed 2026-09-11
- Addepar Unveils Addison, a Native AI Experience Built to ...Source accessed 2026-09-11
- Buyout firm Vista explores $3 billion sale of private markets ...Source accessed 2026-09-11
- Allvue Launches GP Accounting Solution to Unify Fund and Firm EconomicsSource accessed 2026-09-11
- eFront - Alternative Investment Management | BlackRockSource accessed 2026-09-11
- Integrated Private Markets Technology | AladdinSource accessed 2026-09-11
- BlackRock to buy French software firm eFront for $1.3 ...Source accessed 2026-09-11
- Best Fund Administration Software for Private Equity (2026)Source accessed 2026-09-11
- Dasseti: Due Diligence Software | ESG Data Exchange | RFP ...Source accessed 2026-09-11
- Nasdaq Completes Acquisition of Dasseti, Deepening Nasdaq eVestment's AI and Private Markets CapabilitiesSource accessed 2026-09-11
- Nasdaq completes acquisition of DassetiSource accessed 2026-09-11
- Strategic Partnership Highlight: Archway's Platform℠ x ...Source accessed 2026-09-11
- Alternative Investment Solutions Software | AccelexSource accessed 2026-09-11
- Addepar Pricing in 2026: What It Actually Costs, Who It's ...Source accessed 2026-09-11
- Addepar vs. Aladdin: Which is Better for RIAs?Source accessed 2026-09-11
- Deal Origination Software That Helps You Close (2026)Source accessed 2026-09-11
- Midaxo Software Reviews, Demo & Pricing - 2026Source accessed 2026-09-11
- How much does a data room cost? | FAQSource accessed 2026-09-11
- Datasite Review 2026: The Per-Page Bill and 7 ...Source accessed 2026-09-11
- Best LP Reporting Software for Private Equity (2026)Source accessed 2026-09-11
- Addepar Review 2026: Platform, Pricing &… - Andsimple.coSource accessed 2026-09-11
- Affinity vs Intapp Deal Cloud (2026): Which Is Better? - RFP.wikiSource accessed 2026-09-11
- Intapp Pricing, Reviews, Pros & Cons (2026)Source accessed 2026-09-11
- Midaxo Pricing 2026Source accessed 2026-09-11
- Intapp (INTA) Q3 2026 Earnings Transcript | The Motley FoolSource accessed 2026-09-11
- Firm AI for Private Capital | Amplify 2026Source accessed 2026-09-11
- NASDAQ: INTA Intapp Inc Stock Ownership - Who owns ...Source accessed 2026-09-11
- M&A Intelligence Platform | Midaxo M&A SoftwareSource accessed 2026-09-11
- Midaxo - Reviews - End-to-End M&A Process SoftwareSource accessed 2026-09-11
- Midaxo Software Pricing & Plans 2025: See Your CostSource accessed 2026-09-11
- Datasite · Rating Snapshot: Score & Reviews (2026) - RFP.wikiSource accessed 2026-09-11
- Datasite to Acquire Sourcescrub, Expanding Private Market ...Source accessed 2026-09-11
- What are the best deal sourcing platforms in 2026? | InvenSource accessed 2026-09-11
- Affinity Pricing: Plans for Private Capital CRMSource accessed 2026-09-11
- Altss vs Affinity (2026): Allocator Data vs Relationship CRMSource accessed 2026-09-11
- M&A Platform — Pipeline, Diligence, Integration & MoreSource accessed 2026-09-11
- 4Degrees Pricing, Reviews, Pros & Cons (2026) - ProspeoSource accessed 2026-09-11
- Pricing - 4DegreesSource accessed 2026-09-11
- 4Degrees CRM Review 2026: Is It Worth It for Small VC ...Source accessed 2026-09-11
- CorpDev.Ai - Agentic AI for M&A and Corporate DevelopmentSource accessed 2026-09-11
- CorpDev.Ai vs DealRoom Pipeline: Free Zero-Entry CRM vs Manual ...Source accessed 2026-09-11
- Pricing - CorpDev.AiSource accessed 2026-09-11
- AI Analyst Agent for M&ASource accessed 2026-09-11
- CorpDev.Ai Revenue, Funding & Valuation - ProspeoSource accessed 2026-09-11
- About UsSource accessed 2026-09-11