
M&A Strategy Development
An M&A strategy is a set of choices about where ownership can improve the enterprise, what the company is willing to pay to achieve that improvement, and what it can actually absorb. It should help leadership reject plausible deals as effectively as it helps identify attractive ones.
The strategy is ready to use when a business sponsor and deal team can apply it to an unfamiliar target and reach a reasoned screening decision. “Expand internationally,” “acquire technology,” and “consolidate the market” are starting points; each needs a specific value mechanism, a credible alternative, and a test that could disprove it.
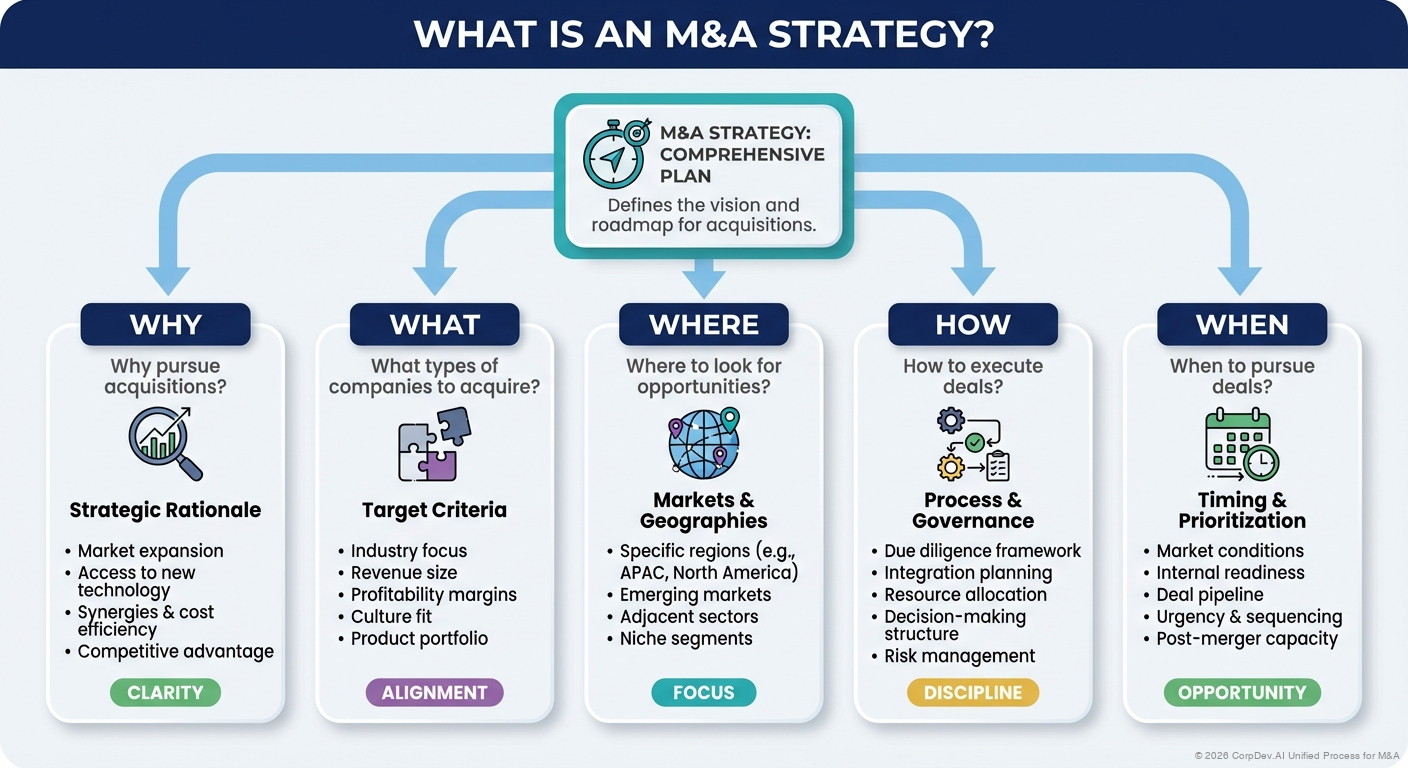 Write an investable M&A thesis ↗Why: strategic rationale ↗What: target criteria ↗Where: markets and geographies ↗How: process and governance ↗When: integration capacity and priorities ↗
Start with an operating problem
Describe the gap in the enterprise plan before describing a target. Identify the affected customer, product, capability, geography, or cost position. Establish the baseline: what happens if the company continues its currently funded plan without a transaction?
Ask the business sponsor for evidence already available inside the company: lost bids, customer interviews, product roadmap constraints, capacity data, channel economics, and returns on prior investments. A strategy team estimate is useful context; the operating evidence should explain why action is necessary.
For each gap, distinguish urgency from management preference. A customer commitment with a dated delivery requirement creates a different time constraint from a general desire to accelerate growth. Avoid assuming an acquisition is faster: diligence, approvals, integration, product adaptation, and customer migration can all sit on the critical path.
Compare routes to the same outcome
Evaluate build, buy, partner, license, invest, and defer against the same target outcome. Do not compare a fully costed acquisition with an unfunded internal aspiration, or a perfect acquisition with a deliberately weak build case.
| Question | Evidence to request | Accountable contributor |
|---|---|---|
| What capability is needed? | Customer requirements and acceptance criteria | Business or product leader |
| When is it economically useful? | Demand milestones and consequences of delay | Business sponsor |
| Can we develop it? | Costed roadmap, hiring needs, dependencies, and delivery risks | Engineering or operations |
| Can a partner supply it? | Commercial terms, service requirements, control limits, and switching options | Business development and counsel |
| Does ownership add value? | Incremental cash flow, control benefits, and integration demands | CorpDev and finance |
| Can the enterprise execute? | Named leadership, change calendar, and constrained resources | Integration leader and functional executives |
The output should show the preferred route, the strongest alternative, and the condition under which leadership would change its choice.
Write an investable thesis
Use one thesis per distinct value mechanism. A capability acquisition and a cost consolidation may involve the same sector but require different target screens and integration plans.
A reusable thesis contains:
- Enterprise objective: The measurable operating outcome and responsible executive.
- Ownership logic: What owning the asset enables that the alternatives cannot achieve economically.
- Target characteristics: Required capabilities, business quality, customer fit, and relevant footprint.
- Exclusions: Features that undermine the thesis, even if the business appears attractive.
- Value mechanism: The actions that produce incremental cash flows, with dependencies and timing.
- Evidence plan: The facts needed to advance, and which assumptions remain untested.
- Integration concept: What will be combined, preserved, or separated, and why.
- Capital and capacity requirements: Purchase funding, implementation costs, leadership time, and operating investment.
- Disconfirming evidence: Findings that would cause the company to stop or change approach.
- Review trigger: A change in strategy, economics, competition, or execution capacity that requires reconsideration.
Keep target fit separate from seller willingness. A motivated seller does not make a weak thesis stronger; an unavailable high-fit company can remain valuable market intelligence.
Set financial discipline without false precision
Finance should establish valuation conventions and return criteria that fit the company's capital allocation framework. Specify how teams treat taxes, working capital, capital expenditure, integration costs, financing, and residual value. Use consistent enterprise-value or equity-value bases throughout the analysis.
A useful conceptual test is:
Buyer net value = standalone value acquired + present value of incremental benefits − consideration paid − present value of incremental transaction and integration costs.
Apply the terms consistently and avoid double counting costs or benefits already included in standalone value. If describing the price as a premium over standalone value, buyer net value is the incremental benefits less that premium and incremental costs. A strategic label does not make a negative result acceptable without an explicit, separately justified leadership decision.
Model downside cases around the actual thesis. For a product acquisition, test slower adoption, engineering dependencies, and retention. For a consolidation, test customer attrition, stranded overhead, and delayed facilities actions. Show whether the enterprise can fund the downside as well as whether the expected return is attractive.
Allocate scarce integration capacity
Several individually attractive acquisitions may form an unexecutable portfolio. Map their demands on the same leaders, systems, customers, and capital. Identify which initiatives depend on the same ERP program, salesforce redesign, or product architecture decision.
A portfolio review should compare expected value with bottleneck consumption. Sequencing can matter more than adding another target to the pipeline. Name the executive who can release constrained resources, and document which existing work will be delayed if a new deal proceeds.
A hypothetical strategy test
Assume an industrial company wants to add remote diagnostics to its installed base. The initial thesis is to acquire a software provider because its product appears mature.
The product leader finds that deployment requires hardware changes on older machines. Commercial diligence shows customers want uptime guarantees rather than another software subscription. The acquisition may still be attractive, but the original “sell software to the installed base” case no longer describes the work required.
The revised decision compares acquiring the platform with licensing it for a service pilot. It includes retrofit costs, service obligations, data access, and operating capability. The thesis advances only if the sponsor accepts those costs and the customer evidence supports the service model. These are illustrative choices, not industry benchmarks.
Make the strategy usable in live deal decisions
Translate approved theses into screening fields and a short decision memo. For opportunities outside the mandate, require an explicit exception explaining why the strategy should change; do not quietly relabel the target to fit.
At each strategy review, bring evidence from both acquired and rejected targets. Examine whether underwriting errors came from the thesis, target selection, price, or execution. Preserve the original thesis so changes are visible. Rewriting history to match outcomes prevents learning.
Connect this work to building an M&A pipeline, strategic rationale, and approval gates.
© 2026 CorpDev.Ai Unified Process for M&A