
Post-Merger Integration (PMI)
Post-merger integration is the work that turns a signed deal into the results that justified it. It protects the business you bought, delivers the benefits in the investment case, and manages the changes the deal forces on both companies.
The right approach follows the thesis. Some parts of the target must be combined with yours; others are valuable because they work differently. Standardize everything and you can damage what you paid for. Preserve everything and the benefits of owning it may never arrive.
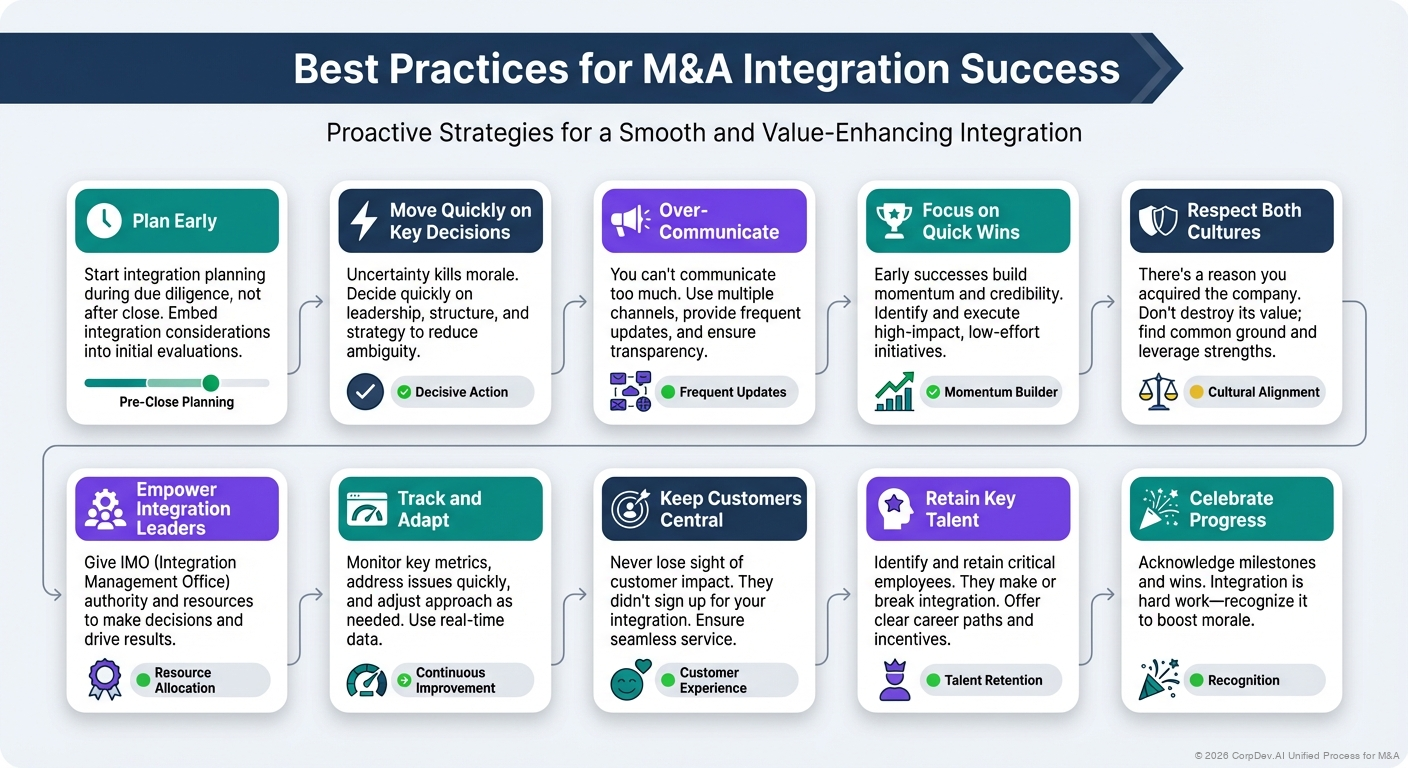 Plan early ↗Move quickly on key decisions ↗Communicate throughout the transition ↗Focus on quick wins ↗Respect both cultures ↗Empower integration leaders ↗Track and adapt ↗Keep customers central ↗Retain key talent ↗Recognize progress ↗
Decide what to combine, keep, or leave alone
Before signing, choose an approach for each area of the business: leadership, customers, brand, product, technology, sales, finance, people, legal entities, and shared services. For each area, decide whether to combine, preserve, connect, or separate it, and write down the value or control need behind the choice.
The table shows the questions that drive those choices and who should answer them.
| Question | Evidence needed | Who decides |
|---|---|---|
| What must stay distinctive? | What customers value, critical capabilities, and operating dependencies | Business sponsor |
| What must change to deliver the thesis? | How each benefit is produced, costed actions, and a feasibility check | Benefit owner and finance |
| What is essential for continuity and control? | Operating, financial, security, and legal requirements | Relevant functional executive |
| What can wait? | Dependencies and the cost of waiting | Integration leader and business owner |
| What capacity will the buyer commit? | Named people, funding, and competing change programs | Executive sponsor |
These are decisions, not a general preference for "fast" or "light" integration. Different parts of one business may need different approaches.
Plan before closing, within legal limits
Integration should shape diligence, valuation, and terms. While you can still change the case, identify the major systems dependencies, leadership needs, customer commitments, transition services, and costs.
Counsel defines what information may be shared and what planning is permitted before closing. For deals between competitors, the FTC emphasizes safeguards against misuse of competitively sensitive information during integration planning as well as diligence. FTC guidance.
A planning assumption is not a commitment from the target's managers or employees. Record what has been discussed, what is permitted, what is still unconfirmed, and how that uncertainty affects readiness.
Give the integration office authority, not just a plan
Roles need to be explicit:
- The integration leader coordinates the plan, dependencies, decisions, and escalation.
- Functional executives deliver within their areas.
- The business owner owns operating results.
- Finance validates the benefit baseline and reports what is actually realized.
Give the integration leader direct access to the executive sponsor and a clear route for settling competing priorities. A coordinator without that access cannot resolve a conflict between a major customer commitment and a central systems migration.
Keep a short set of records: the milestone plan, decision log, issue register, benefit ledger, dependency map, budget, and readiness dashboard. Link them, so a delayed prerequisite updates the milestone and the benefit that depend on it.
Make Day 1 a test of continuity
Day 1 readiness means the business can operate safely and reliably the moment the deal completes. It is not the deadline for every optional change.
A practical readiness review asks:
- Who is in charge, and can employees reach the people who make urgent decisions?
- Can the business pay employees and suppliers, collect cash, and serve customers?
- Are critical systems, access, support arrangements, and incident contacts in place?
- Do people understand the policies, reporting lines, and approved communications that apply?
- Do the agreed transition arrangements cover every dependency on the seller?
- Have critical customer and employee communications been coordinated and approved?
- Does each major cutover have a tested fallback and one owner for the go or no-go call?
Require evidence from functional owners, not self-reported green status. A written payroll plan and a tested ability to run payroll are different levels of readiness.
Rehearse Day 1 with the functional owners
Walk through Day 1 with the people responsible for employees, customers, payments, access, and operations. For each critical activity, confirm the owner, prerequisite, fallback, and evidence that it works. Resolve gaps before closing or record an approved contingency. Counsel should direct any pre-close coordination with the target.
Sequence the plan by dependencies and capacity
Order the work by prerequisites and business consequences. A sales force combination may depend on compensation design, account ownership, product compatibility, and customer consent. An ERP migration may depend on data quality, process decisions, and financial reporting needs.
Choose planning horizons that fit the deal. "First 100 days" is a useful communication label, not a universal deadline. Define near-term stabilization, the priority value initiatives, and later operating changes, each with realistic decision points.
Map what integration demands of the buyer's existing organization. It may compete with a product launch, another acquisition, or a finance transformation. Say what will be deprioritized instead of assuming the same people can deliver every program at once.
Compare the milestone plan regularly with workstream updates, transition-service schedules, and the decision log to catch missing prerequisites and conflicting dates. The integration leader confirms each proposed change with functional owners before it enters the plan. A meeting note that says testing is planned must never become "testing complete" on the dashboard.
Prove value one initiative at a time
Each value initiative needs a baseline, an accountable operating owner, an action plan, timing, cost to achieve, dependencies, and evidence that it has been realized. Finance keeps three measures apart: annualized run-rate, benefit in the period, and cash effect.
For revenue initiatives, track customer adoption and the added contribution after delivery costs and cannibalization. For cost initiatives, confirm the spending has actually stopped, and identify stranded or replacement costs. Track the damage integration causes, such as lost customers, service disruption, and lost productivity, alongside the benefits.
Keep the original investment case next to current forecasts and actual results. Revising the operating plan may be the right response to new facts, but it must not erase the original case.
A company digital twin can hold the current, Day 1, and target operating states behind the plan. Link each planned change to its prerequisites and proof of completion, so a planned replacement is never mistaken for a dependency already removed.
Manage people and customer uncertainty openly
Identify the critical capabilities and the people or teams they depend on. Settle leadership roles and decision rights early enough to limit confusion. Design retention arrangements around specific business needs, with people, finance, and legal specialists.
Use customer and employee feedback to check whether integration is harming what made the target valuable. Watch for unresolved support cases, delayed renewals, confusion about the roadmap, or unclear management authority, and name who acts on each signal.
Silence is not acceptance. A communication plan needs ways to surface questions and confirm that people understood, especially while organizational or customer-facing changes are still undecided.
Example: when IT and product need the same engineers
This example is hypothetical. It illustrates a choice, not a prescribed timeline.
A buyer acquires a specialist software company for its product and engineering team. Central IT wants to move the target onto the buyer's platform immediately. The product leader needs the same engineers to deliver a release already promised to customers.
The integration team weighs the security and control requirements against the migration's benefits and delivery risks. Leadership might choose interim controls now and a later migration, with a funded plan and a review date. That decision keeps someone accountable for both priorities. Simply declaring the target "autonomous" would leave the security requirement without an owner.
Close the integration office deliberately
Move work into normal operations when the receiving leaders accept the remaining obligations, metrics, budgets, and risks. Confirm that contract deadlines and transition-service exits have owners. Keep reviewing investment performance after the integration office closes.
Report only the scope actually delivered. Leadership reporting should separate three things: operations stabilized, transformation completed, and investment value realized. Each happens on a different timeline and needs different evidence.
Continue with value creation planning, CorpDev metrics, and issue management.
© 2026 CorpDev.Ai Unified Process for M&A